
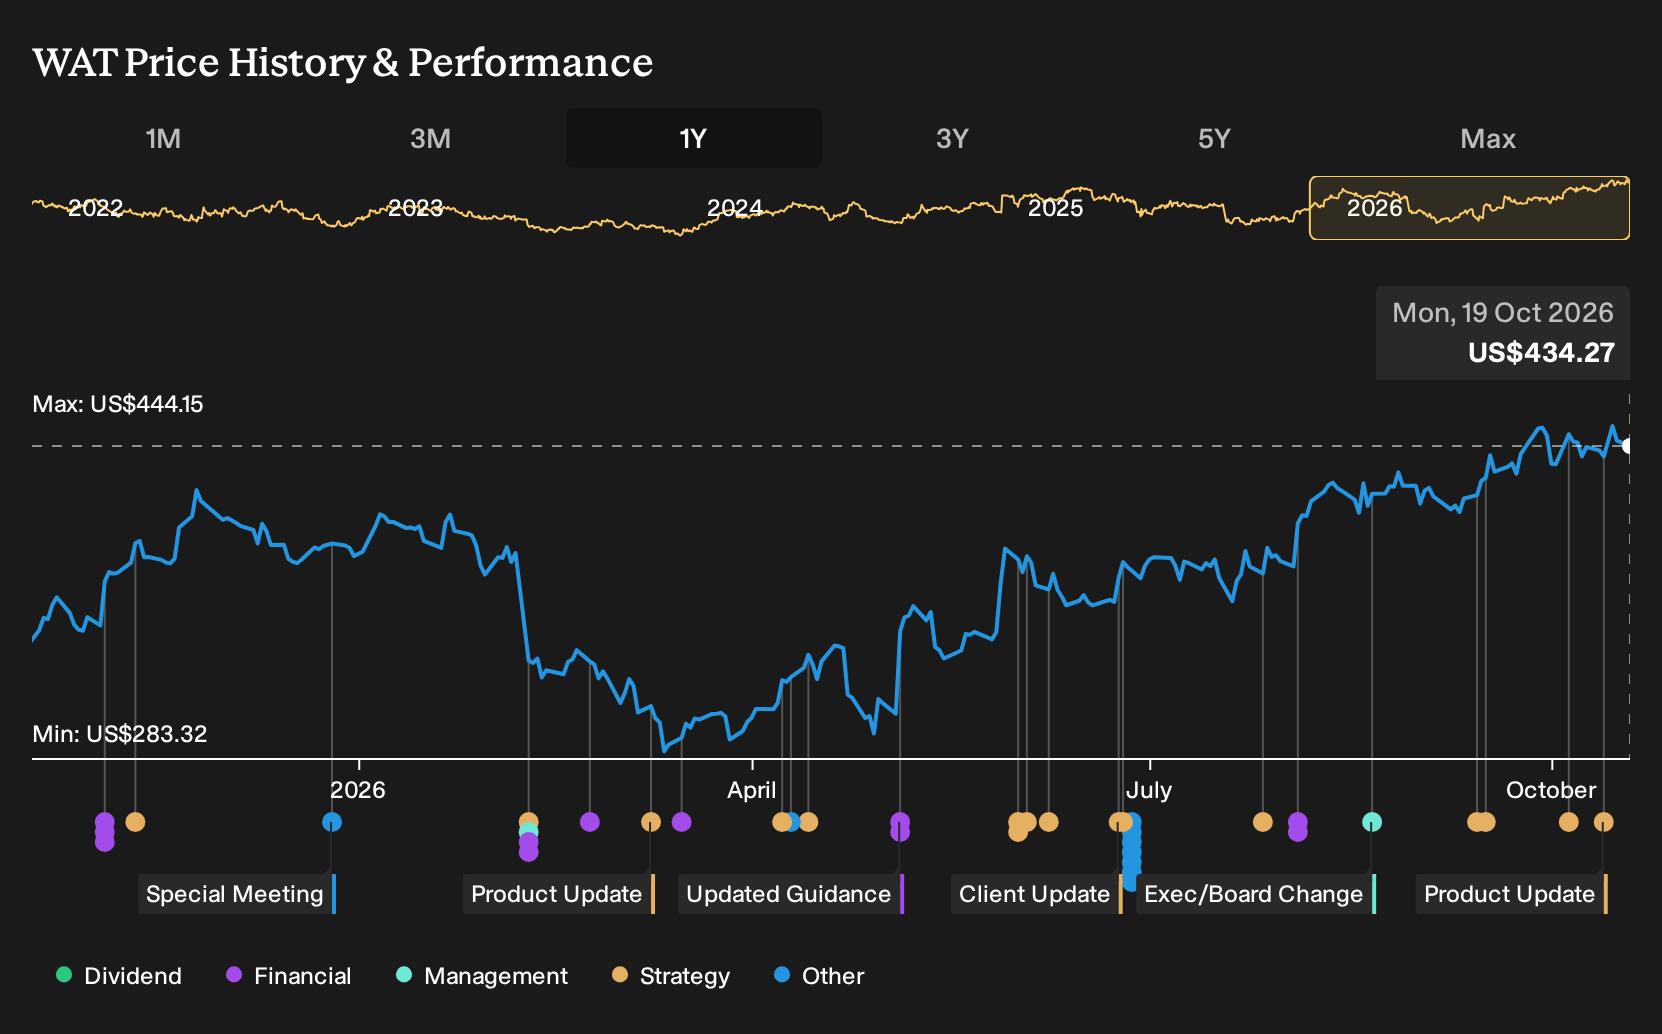
Waters spent this year in the headlines for BD Biosciences integration progress and new LC-MS products such as the Xevo TQ Absolute XR IVD system and Xevo MRT P10. Yet the real story for investors showed up quietly on their statements. Holding Waters over the past year would have returned 26.5%, including dividends. If you were deciding back in October 2025, what needed to be true about LC-MS demand, biotech spending, and BD synergy delivery to justify paying up for that outcome?
Waters is not the only name tied to this theme. Zero in on 33 healthcare AI stocks and compare how each one is priced.
The Two Waters Narratives Investors Had To Weigh
The shares cost US$335 at the start of the period, so anyone looking at Waters then had to decide which story felt more realistic.
The bullish view saw a Fair Value of US$424, a price implied by assumptions of 7.0% yearly revenue growth and profit margins rising to 25.1% helped by LC-MS replacement uptake and BD Biosciences synergies.
The cautious narrative pointed to a Fair Value of US$300 and treated 5.9% annual top line growth plus integration risk at BD as the central concern, with a lower assumed future P/E of 23.4x.
What The Evidence Did To The Waters Thesis
Waters investors saw their LC-MS and BD bets partially validated as Q2 2026 revenue reached US$1.645b compared with US$771m a year earlier, in line with the bullish focus on scale and acquisition leverage. The big catch sat in the income statement. The firm swung from US$147m profit to a loss of US$136m and net margin moved from 19.1% to -8.3%. The evidence cut both ways.
The episode turned on one assumption investors sometimes gloss over, that growth and deal size quickly translate into healthy earnings. When you assess another instrument maker or diagnostics group, track revenue, operating profit and net margin separately to see whether expansion and acquisitions are showing up as durable profitability, not just a bigger top line.
What Waters' Current Price Already Assumes
Waters now trades at US$434, with this Narrative’s Fair Value sitting below that level based on its own modelling. The stock has gained 26.5% over the past year, so today’s buyer is paying for more than the last twelve months of news flow.
The selected Narrative leans on questions about mature LC-MS lines, healthcare budget constraints, and integration risk around BD Biosciences and Diagnostics. To pay today’s price, you would need to judge that customer spending, pricing power, and acquisition synergies all hold up despite those pressures.
"Despite innovation success in its core liquid chromatography and mass spectrometry platforms, with new launches like the Alliance iS and Xevo TQ Absolute driving impressive growth, Waters is heavily reliant on mature product lines, and rapid technological change or adoption of alternative, more automated or decentralized solutions by customers may erode long-term pricing power and compress gross margins."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Where Waters' Demand Can Point Next
Follow Waters long enough and one pattern becomes hard to ignore. Sophisticated tools keep pushing for more capable computing muscle behind the scenes.
The same labs and data centers that handle complex LC-MS workflows also depend on heavy-duty memory and storage to move data quickly.
Another business focuses almost entirely on supplying that capacity, giving AI servers the working room their chips need.
Its challenge differs from Waters. Staying relevant means huge factories, long contracts, and constant bets on how AI workloads evolve.
Could this be another way into the opportunity? → Explore the AI infrastructure opportunity and its 28% discount to one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com