
- ResMed has launched the AirTouch F40 CPAP mask in the U.S., adding a fabric, minimalist full-face option that integrates with its connected sleep platform and is intended to support long term obstructive sleep apnea therapy adherence.
- The mask’s broad fit range, interchangeable cushion with AirFit F40, and linkage to myAir and AirView underline how ResMed is tying hardware design to digital tools to support therapy compliance and recurring mask demand.
- We will now assess how this focus on fabric comfort and adherence centric design could influence ResMed's broader investment narrative.
ResMed Investment Narrative Recap
To own ResMed, you need to believe in a long runway for sleep and breathing health, and in the company’s ability to convert that into recurring device, mask and software usage. The AirTouch F40 launch fits that story by emphasizing comfort and adherence, but on its own it does not change the near term picture.
The more immediate swing factors remain execution on gross margin in the face of component and freight cost pressures, and managing the Astral field corrective action that is expected to weigh on FY2027 earnings. New masks like AirTouch F40 matter most if they offset MatrixCare divestment drag and keep the sleep ecosystem attractive for patients and providers.
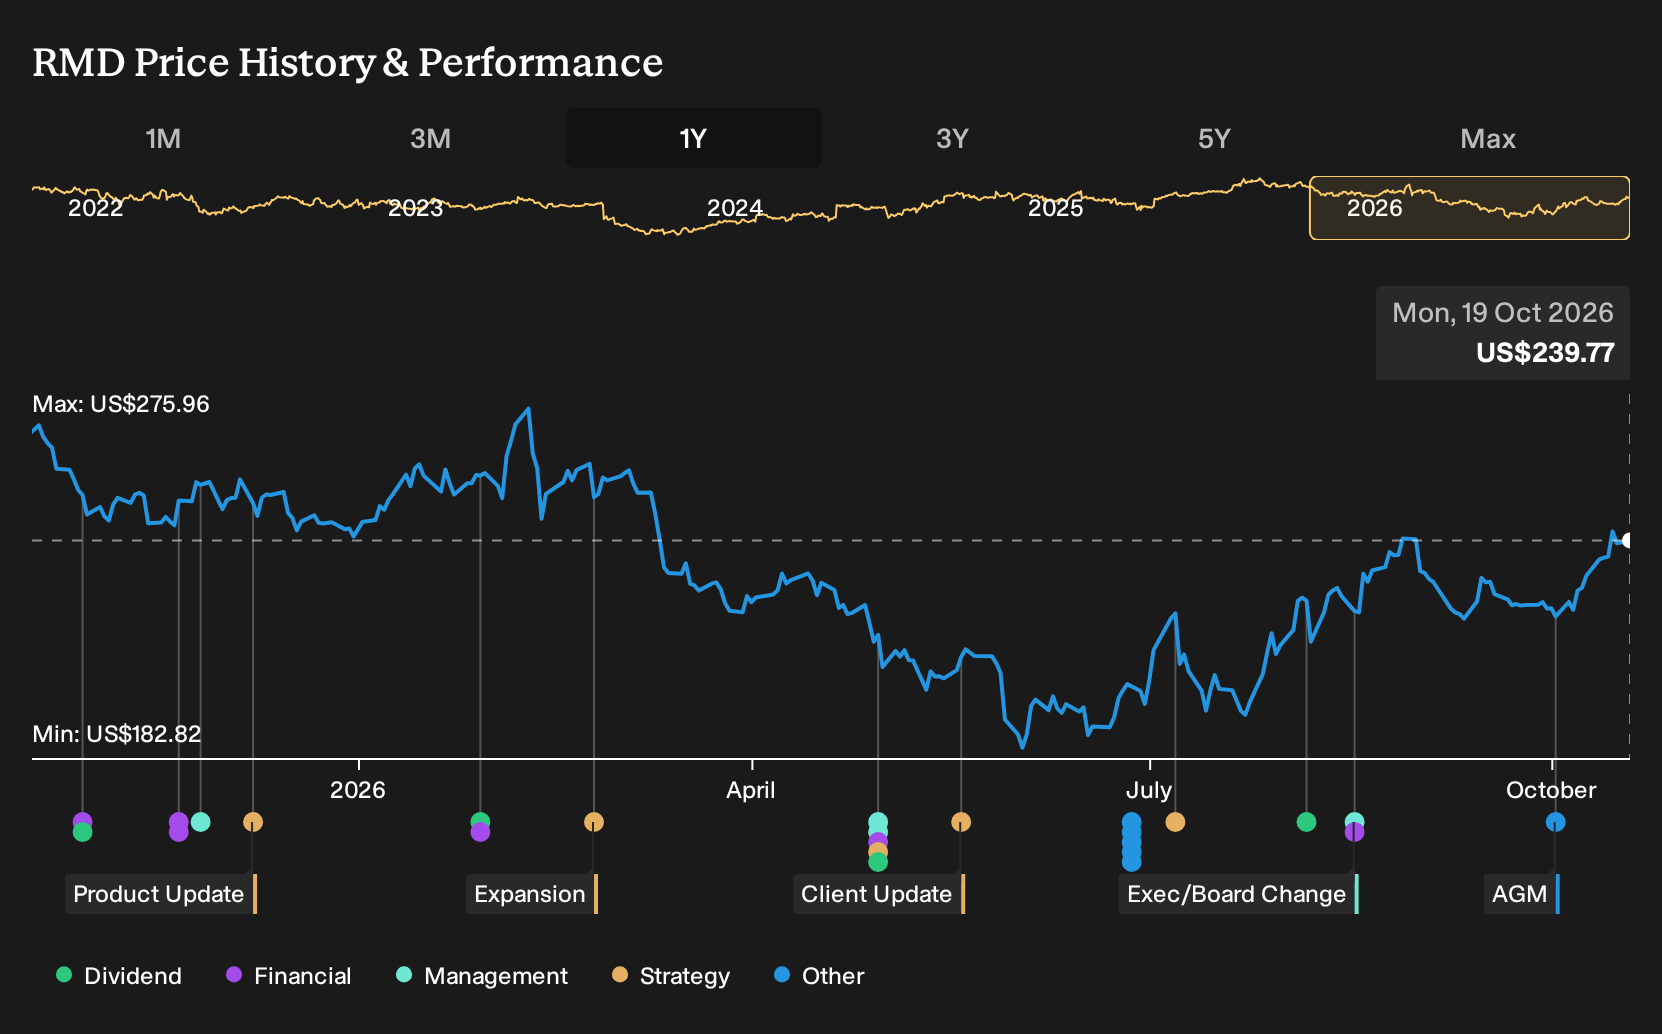
The most relevant recent development in this story is ResMed completing a long running share repurchase program. Between July and September 2026, the business bought back 972,000 shares for US$200 million, bringing total repurchases under the plan to 13,054,030 shares for US$1.76 billion, or 9.13% of the company.
This capital return sits alongside product launches such as AirTouch F40 and illustrates management using both financial and operating levers. For you as a shareholder, the key question is whether ongoing buybacks, product refreshes and software driven adherence can collectively offset risks from Astral remediation, cost inflation and the revenue removed with MatrixCare.
What The AirTouch F40 Means Against Consensus Numbers
ResMed's narrative projects US$6.6b revenue and US$1.9b earnings by 2029. This aligns with analyst assumptions for 5.3% yearly revenue growth and an earnings increase of about US$400m from US$1.5b today.
Uncover why ResMed's fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The most optimistic analysts focus on ResMed’s fabric mask portfolio as the real swing factor for the story. Before this AirTouch F40 launch, the bullish camp was already modeling revenue of about US$6.8b and earnings of roughly US$1.8b by 2029. That is a far richer setup than consensus, and it shows how far opinions can stretch. Use this new fabric launch as a prompt to compare those different forecasts and decide which version of the future you find more realistic.
Explore 4 other ResMed fair value estimates, including one that suggests as much as 53% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ResMed research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for ResMed. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ResMed's overall financial health at a glance.
Looking For More Ideas Beyond ResMed?
Once you have formed a view on ResMed, it often helps to cross check that thesis against other companies with different risk and return profiles. The Simply Wall St Screener can surface a range of stocks that match the type of balance sheet strength, value tilt or income profile you want to focus on next.
- If you want potential value combined with quality fundamentals, scan a 35 high quality undervalued stocks that already clear high bars on both cash flow and balance sheet strength.
- For investors who prefer steadier profiles with fewer red flags, filter for 32 resilient stocks with low risk scores that our models rate as more resilient on multiple risk checks.
- If you are hunting for future leaders before they are widely followed, target a 20 high quality undiscovered gems that pair solid financials with relatively low current visibility in the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com