
In the last week, the United States market has stayed flat but is up 14% over the past year with earnings forecasted to grow by 17% annually. In this context, identifying stocks that may be undervalued could present opportunities for investors seeking potential discounts in a rising market environment.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $62.68 | $123.11 | 49.1% |
| TD SYNNEX (SNX) | $273.06 | $526.32 | 48.1% |
| Pegasystems (PEGA) | $34.91 | $69.69 | 49.9% |
| M&T Bank (MTB) | $219.89 | $422.75 | 48% |
| KeyCorp (KEY) | $20.09 | $39.70 | 49.4% |
| EOG Resources (EOG) | $150.51 | $296.27 | 49.2% |
| Civista Bancshares (CIVB) | $26.71 | $53.30 | 49.9% |
| Cencora (COR) | $325.06 | $625.02 | 48% |
| Amkor Technology (AMKR) | $48.11 | $96.01 | 49.9% |
| Addus HomeCare (ADUS) | $115.475 | $226.18 | 48.9% |
Below we spotlight a couple of our favorites from our exclusive screener.
Alphabet (GOOGL)
Overview: Alphabet Inc. operates a diverse range of products and platforms across multiple regions including the United States, Europe, the Middle East, Africa, the Asia-Pacific, Canada, and Latin America with a market cap of $4.29 trillion.
Operations: The company's revenue is primarily derived from Google Services at $367.09 billion and Google Cloud at $77.62 billion, with additional contributions from Other Bets totaling $1.51 billion.
Estimated Discount To Fair Value: 30.7%
Alphabet is currently trading at US$352.72, significantly below its estimated future cash flow value of US$508.75, suggesting it is undervalued by over 20%. Despite a forecasted decline in earnings by 0.2% annually for the next three years, revenue is expected to grow faster than the US market at 17.4% per year. Recent strategic partnerships and initiatives in AI and gaming could enhance long-term cash flows despite ongoing legal challenges and regulatory fines.
- Our earnings growth report unveils the potential for significant increases in Alphabet's future results.
- Click here and access our complete balance sheet health report to understand the dynamics of Alphabet.
General Dynamics (GD)
Overview: General Dynamics Corporation is a global aerospace and defense company with a market capitalization of approximately $90.62 billion.
Operations: The company's revenue is derived from four main segments: Aerospace ($13.83 billion), Technologies ($13.76 billion), Combat Systems ($9.36 billion), and Marine Systems ($17.92 billion).
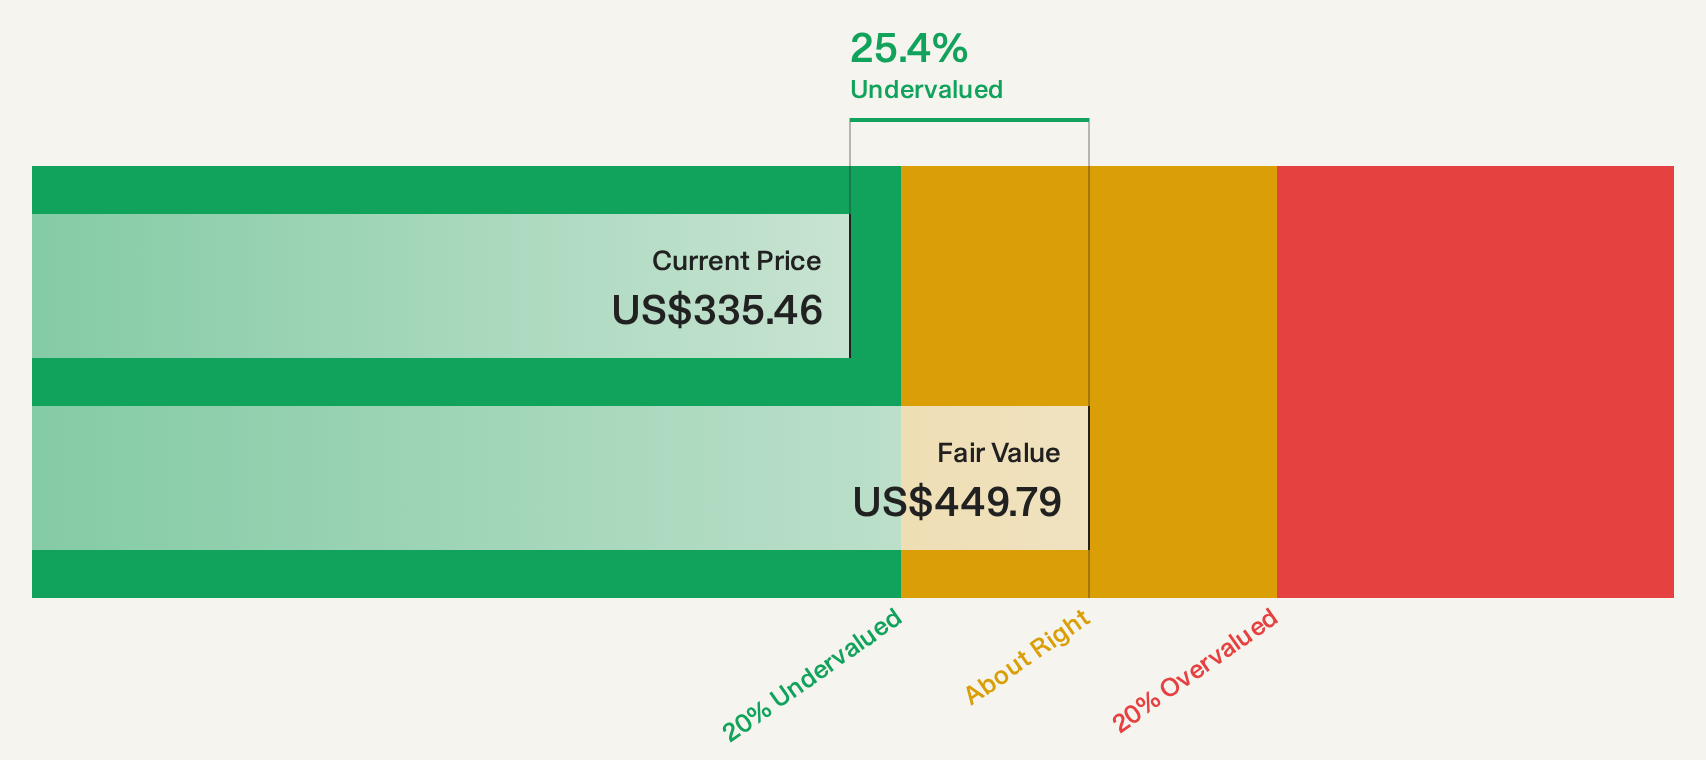
Estimated Discount To Fair Value: 25.4%
General Dynamics is trading at US$335.46, below its estimated future cash flow value of US$449.79, indicating it is undervalued by over 20%. Despite slower forecasted revenue growth of 4.1% annually compared to the broader market, earnings are expected to grow at 7.34% per year. Recent leadership changes with Danny Deep as incoming CEO could influence strategic directions, while consistent dividends and share buybacks reflect strong cash management practices.
- Our growth report here indicates General Dynamics may be poised for an improving outlook.
- Take a closer look at General Dynamics' balance sheet health here in our report.
U.S. Bancorp (USB)
Overview: U.S. Bancorp is a financial services holding company that offers a range of financial services to individuals, businesses, and institutions across the United States with a market cap of approximately $89.46 billion.
Operations: The company's revenue segments include Payment Services at $5.97 billion, Consumer and Business Banking at $8.61 billion, Treasury and Corporate Support at $392 million, and Wealth, Corporate, Commercial and Institutional Banking at $12.47 billion.
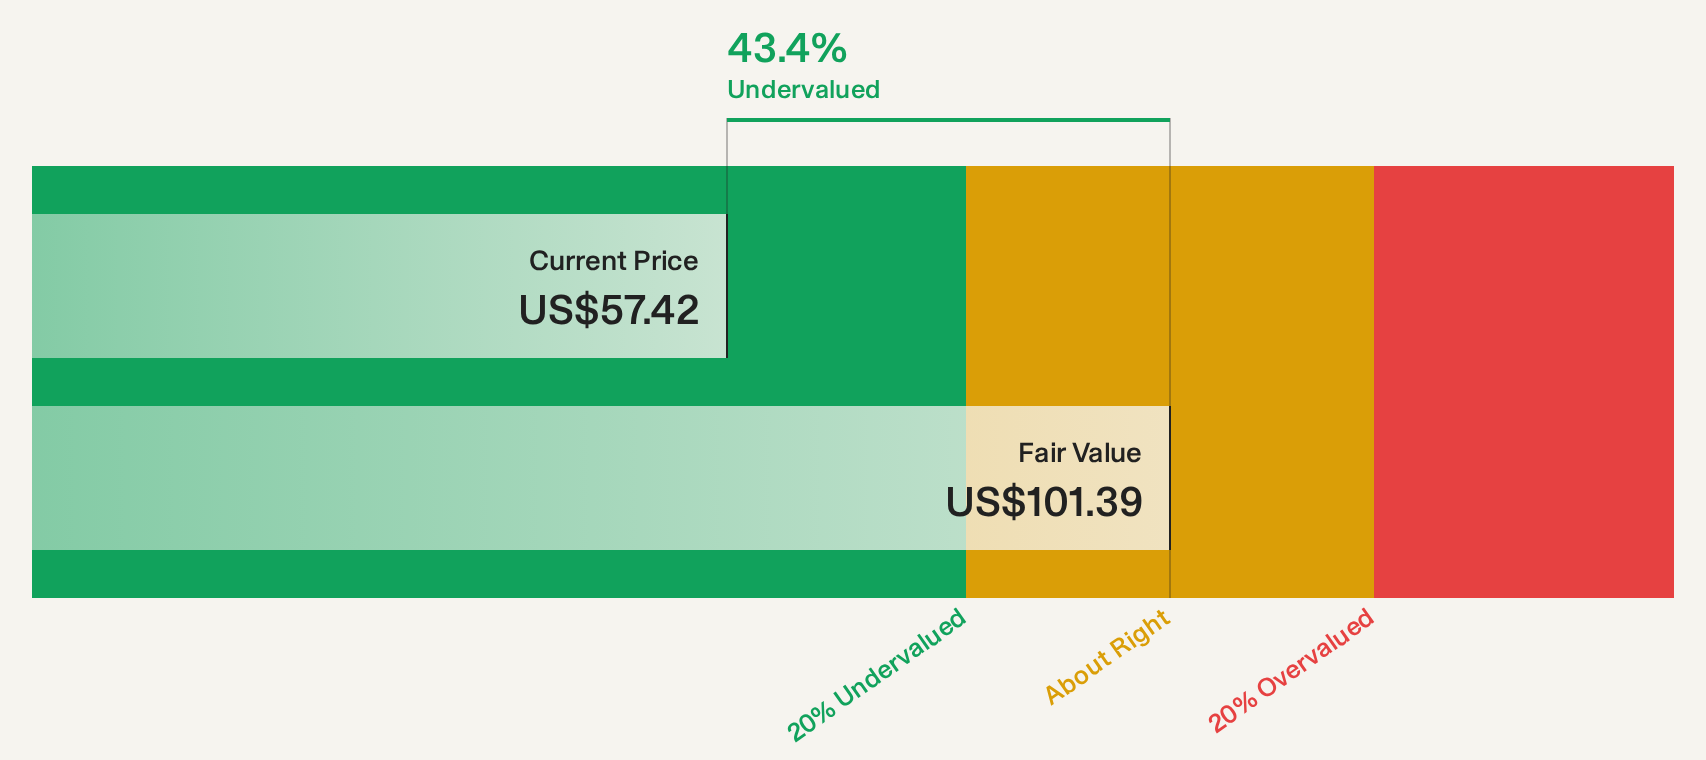
Estimated Discount To Fair Value: 43.4%
U.S. Bancorp is trading at US$57.42, significantly below its estimated future cash flow value of US$101.39, suggesting undervaluation based on cash flows. Despite slower forecasted revenue growth of 9.5% annually compared to the market, earnings are expected to grow at 6.44% per year. Recent debt redemption and product launches like Protect 360 reflect strategic financial management and innovation in services, enhancing client offerings while maintaining consistent dividend payouts.
- In light of our recent growth report, it seems possible that U.S. Bancorp's financial performance will exceed current levels.
- Unlock comprehensive insights into our analysis of U.S. Bancorp stock in this financial health report.
Seize The Opportunity
- Delve into our full catalog of 97 Undervalued US Stocks Based On Cash Flows here.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com