
Over the last 7 days, the United States market has remained flat, yet it has seen a notable increase of 15% over the past year with earnings forecasted to grow by 18% annually. In this context, identifying stocks priced below their estimated fair value can be a strategic approach for investors looking to capitalize on potential growth opportunities.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $62.49 | $123.11 | 49.2% |
| Pegasystems (PEGA) | $35.65 | $69.63 | 48.8% |
| M&T Bank (MTB) | $217.49 | $422.24 | 48.5% |
| KeyCorp (KEY) | $19.97 | $39.68 | 49.7% |
| Insteel Industries (IIIN) | $29.50 | $57.36 | 48.6% |
| Gilat Satellite Networks (GILT) | $8.94 | $17.27 | 48.2% |
| EOG Resources (EOG) | $148.16 | $296.27 | 50% |
| Artisan Partners Asset Management (APAM) | $33.46 | $65.03 | 48.5% |
| Amkor Technology (AMKR) | $49.12 | $96.22 | 48.9% |
| Addus HomeCare (ADUS) | $114.33 | $226.18 | 49.5% |
Let's take a closer look at a couple of our picks from the screened companies.
MYR Group (MYRG)
Overview: MYR Group Inc., with a market cap of $4.85 billion, operates through its subsidiaries to provide electrical construction services in the United States and Canada.
Operations: The company's revenue is primarily derived from its Commercial & Industrial segment, generating $1.91 billion, and its Transmission & Distribution segment, contributing $2.10 billion.
Estimated Discount To Fair Value: 40.3%
MYR Group trades at a significant discount to its estimated future cash flow value of US$521.98, with current stock prices reflecting a 40.3% undervaluation. Recent earnings reveal robust growth, with net income nearly doubling year-over-year for Q2 2026. The company secured a substantial credit agreement totaling US$690 million to support acquisitions and growth initiatives, underscoring its strategic focus on expansion while maintaining solid financial health through strong cash flow management.
- Insights from our recent growth report point to a promising forecast for MYR Group's business outlook.
- Navigate through the intricacies of MYR Group with our comprehensive financial health report here.

Moelis (MC)
Overview: Moelis & Company is an investment banking advisory firm with operations across North and South America, Europe, the Middle East, Asia, and Australia, and has a market cap of $4.63 billion.
Operations: The company's revenue segment consists of $1.57 billion from its investment banking advisory services.
Estimated Discount To Fair Value: 34.1%
Moelis & Company is trading at US$57.08, significantly below its estimated future cash flow value of US$86.57, indicating a 34.1% undervaluation relative to fair value estimates. Despite slower earnings growth compared to the market, revenue growth is expected to outpace it slightly. Recent executive appointments aim to bolster advisory capabilities across Europe and the U.S., enhancing strategic depth in financial sponsors and capital solutions sectors amidst a backdrop of stable dividend declarations but significant insider selling concerns.
- The analysis detailed in our Moelis growth report hints at robust future financial performance.
- Delve into the full analysis health report here for a deeper understanding of Moelis.
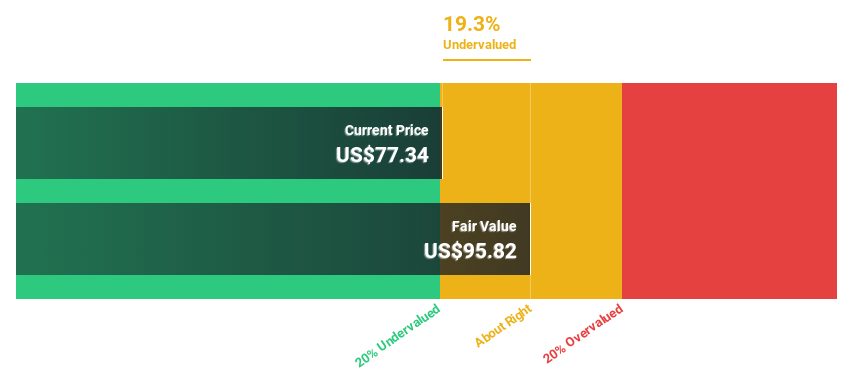
Northpointe Bancshares (NPB)
Overview: Northpointe Bancshares, Inc. is the bank holding company for Northpointe Bank, offering a range of banking products and services in the United States, with a market cap of $547.78 million.
Operations: The company's revenue segments include Retail Banking, generating $165.05 million, and Mortgage Warehouse (MPP), contributing $92.20 million.
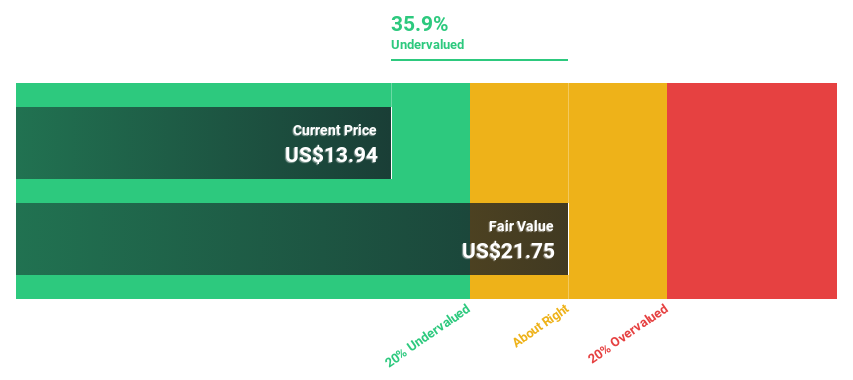
Estimated Discount To Fair Value: 36%
Northpointe Bancshares is trading at US$15.84, below its estimated future cash flow value of US$24.77, reflecting a 36% undervaluation relative to fair value estimates. While earnings are projected to grow at 8.9% annually, slower than the market average, recent leadership changes aim to enhance operational efficiency and strategic growth in the mortgage industry. The company recently increased its quarterly dividend by 20%, signaling confidence in cash flow stability despite modest revenue growth forecasts.
- In light of our recent growth report, it seems possible that Northpointe Bancshares' financial performance will exceed current levels.
- Click to explore a detailed breakdown of our findings in Northpointe Bancshares' balance sheet health report.
Next Steps
- Get an in-depth perspective on all 105 Undervalued US Stocks Based On Cash Flows by using our screener here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com