
Trane Technologies (NYSE:TT) has been busy. Over the past weeks, the company rolled out new cold climate heat pumps, advanced data center cooling systems, and a multi-year sustainability partnership with Kroenke Sports & Entertainment.
For context, Trane Technologies shares now trade at US$476.98, with a 1-month share price return of 7.79% that builds on a 19.84% year-to-date share price gain. The 5-year total shareholder return of 189.16% points to strong long-run compounding, despite a small 90-day pullback of 1.36% as the market digests the latest product launches, data center cooling initiatives and the new Kroenke Sports & Entertainment partnership.
Scan beyond Trane Technologies and compare its AI and cooling momentum with a curated set of 92 AI infrastructure stocks shaping the next wave of data center buildouts.
After a sharp run that leaves Trane Technologies about 6% below one intrinsic value estimate and roughly 11% under the average analyst target, the real question is where fair value actually clusters along that spread.
Most Popular Narrative: 9% Undervalued
On the narrative view, Trane Technologies screens as undervalued, with a fair value estimate of $526.67 against the latest close of $476.98. This comparison puts the spotlight firmly on how that gap could close over time.
Trane Technologies is poised for significant growth in the Commercial HVAC segment, with current record enterprise bookings growth of 37% year over year, a US$12.1b backlog that is up 70% year over year, and sustained strength in Americas commercial and applied bookings supporting potential future revenue and earnings.
See why 36 investors see Trane Technologies as 9% undervalued.
Result: Fair Value of $526.67 (UNDERVALUED)
Still, that story can crack if the US$12.1b backlog slows as data center and non residential projects get deferred, or if pricing fails to offset cost inflation.
Find out about the key risks to this Trane Technologies narrative.
Another View: Trane Technologies Through The P/E Lens
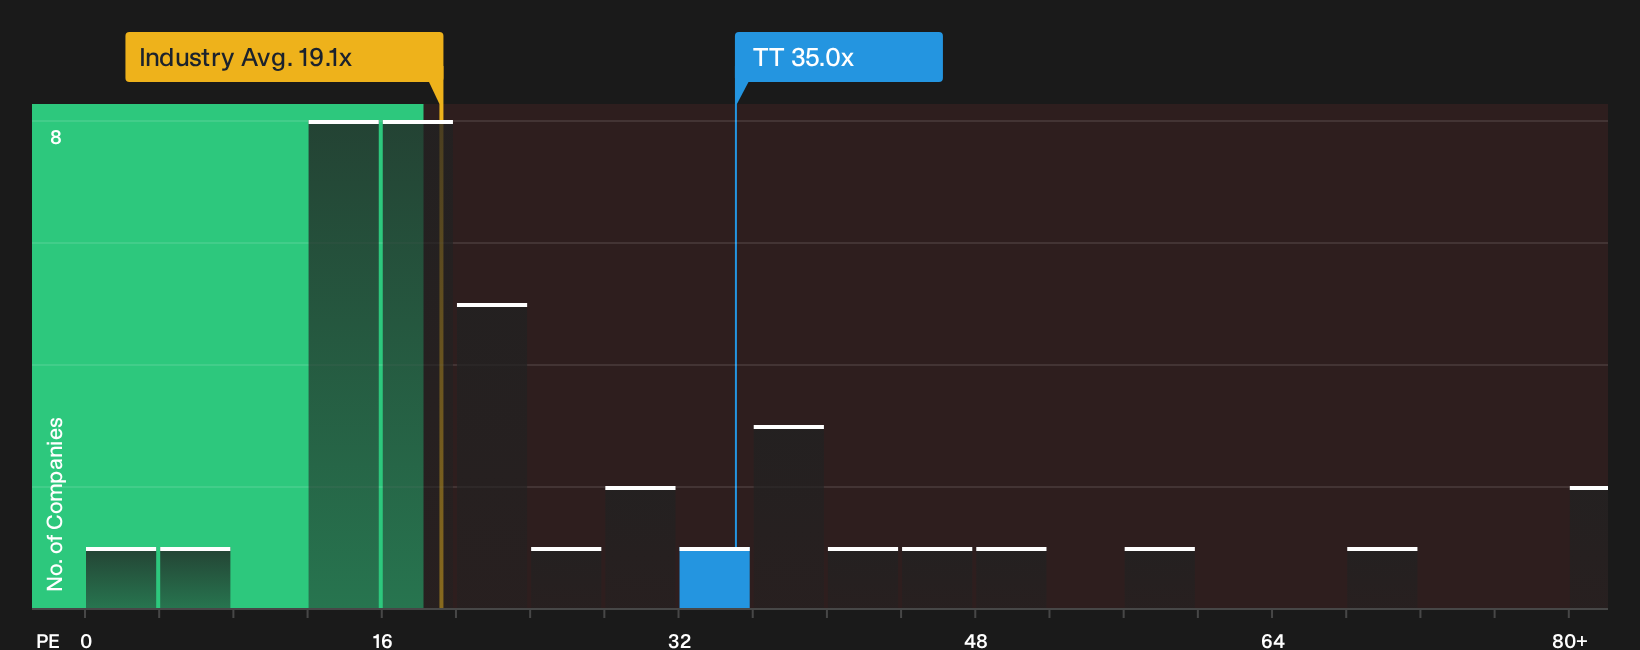
The story shifts once you look at Trane Technologies through its P/E ratio instead of fair value estimates. The shares trade on about 35x earnings, while the fair ratio is 30.4x, the US Building industry averages 19.1x, and peers sit near 29.9x.
That cluster of numbers points to a rich valuation that is well above the sector and even ahead of the fair ratio that the market could move towards over time. For you, the question is whether the backlog, AI cooling exposure and earnings profile justify paying up, or whether that gap simply adds valuation risk.
To pressure test this earnings based view against the detailed valuation work, take a closer look at our breakdown of the numbers and the trade off between quality and price, then weigh it against your own expectations. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling that the Trane Technologies story leans optimistic after all this backlog and AI cooling detail, but still unsure where you land? Put the numbers under your own microscope and weigh the optimism against the risks by starting with 3 key rewards.
Looking for more investment ideas beyond Trane Technologies?
Do not stop with Trane Technologies. Broaden your watchlist with a few focused sets of companies that line up with how you like to balance risk, income, and value.
- Target resilient balance sheets and cleaner fundamentals by scanning a list of solid balance sheet and fundamentals (25 results) that filters for financial strength first.
- Hunt for mispriced quality by reviewing a 29 high quality undervalued stocks that already screens for robust cash flows and healthier balance sheets.
- Stack potential income streams by checking a 8 dividend fortresses built around higher yielding companies that still pass core stability checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com