
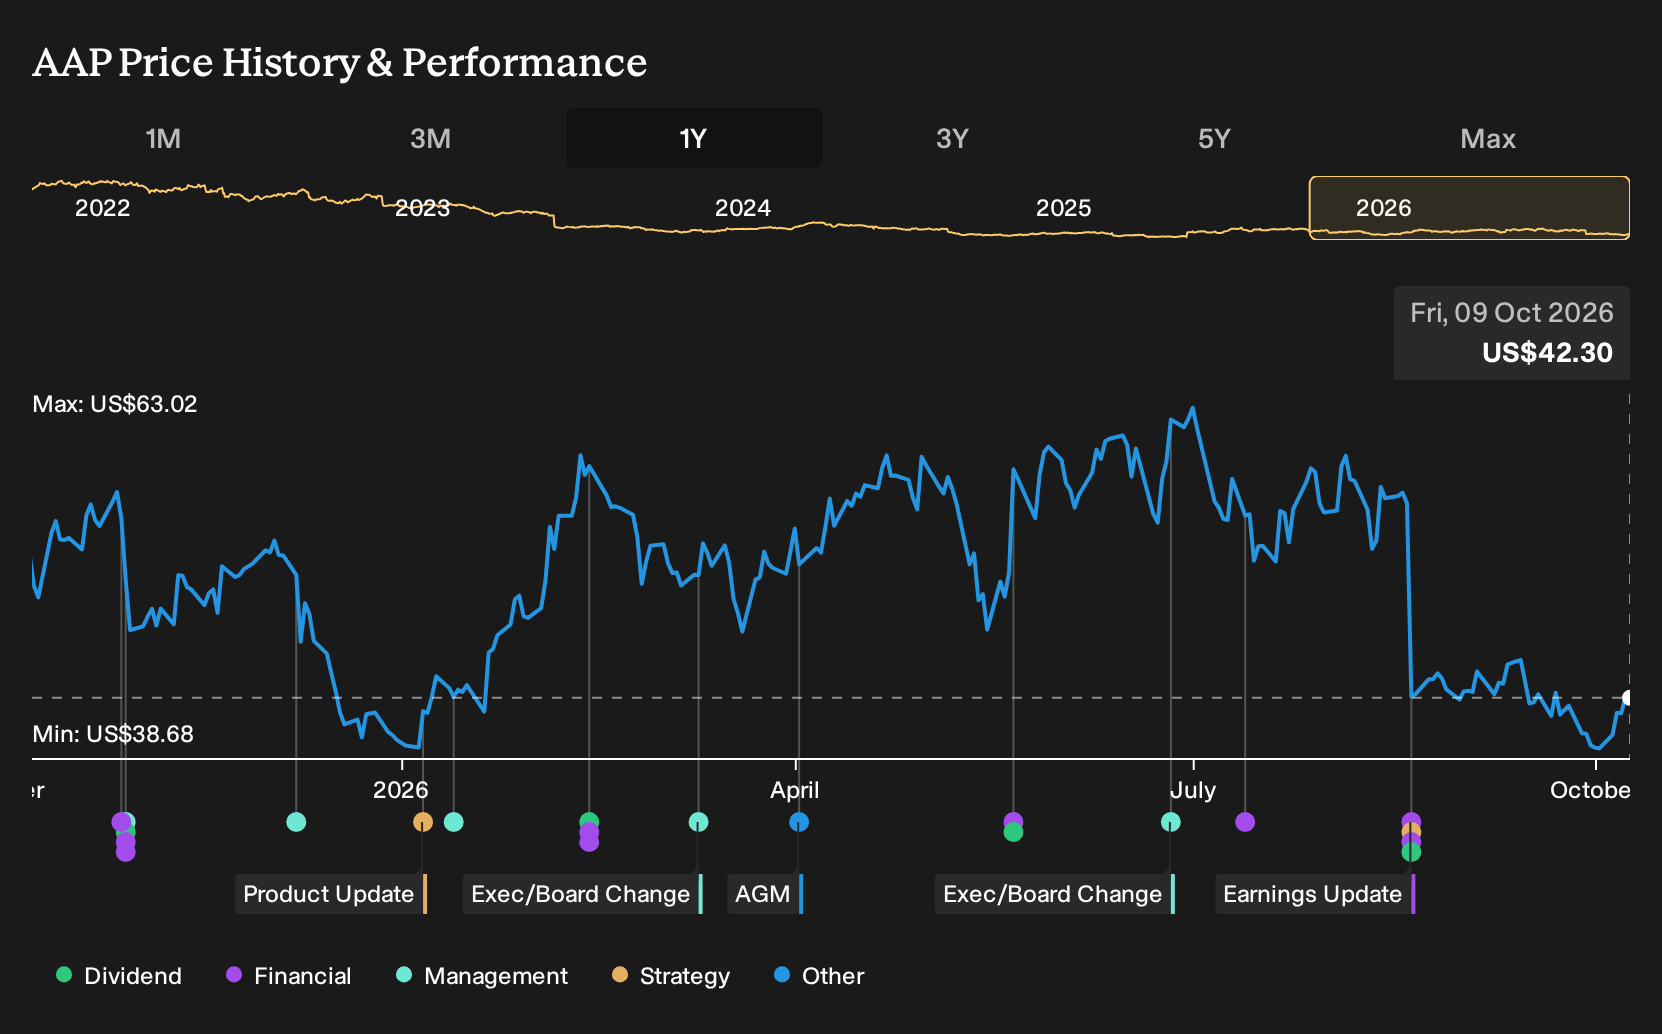
Advance Auto Parts had its strongest Q1 comparable sales performance in five years and swung from an operating loss to a profit, yet the share price reaction over the full year tells a different story. Holding Advance Auto Parts over the past year would have meant a 20.1% loss, including dividends. If you had bought on 9 October 2025, expecting the turnaround headlines to carry the stock, how should you now think about the mix of progress and pressure inside this business?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Advance Auto Parts. Zero in on 29 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Advance Auto Parts
The shares cost US$50.32 at the start of the period. Anyone buying Advance Auto Parts then had to decide which earnings story felt more realistic, not whether a quick rebound was on offer.
The bullish Narrative put Fair Value at US$53.2, based on the planned consolidation of 38 distribution centers into 12 by 2026 and a shift toward vendor partnerships that were expected to support a 3.3% profit margin and a 14.9x future P/E.
The bearish view anchored Fair Value at US$33.5 and focused on long term pressure from electric vehicle adoption, with demand for internal combustion engine parts expected to decline and margins only reaching 2.3% on a 14.2x assumed P/E.
What The Results Changed For Advance Auto Parts
Advance Auto Parts delivered Q2 2026 revenue of US$2.0b compared with US$2.01b a year earlier, while net income moved from US$15m to US$55m and net margin rose from 0.7% to 2.8%. That improvement in profitability, helped by cost and efficiency work, pointed toward the bullish margin ambition, although the flat top line kept the cautious revenue story alive. The evidence cut both ways.
The lesson is simple. When a turnaround rests on margin repair more than sales growth, track net margin and absolute profit first. Then consider whether the revenue trend is strong enough to justify the P/E you are paying in any similar retailer.
What You Are Really Paying For In Advance Auto Parts Today
Advance Auto Parts trades at US$42.3 today, after the stock fell about 20.1% over the past year. The selected Narrative’s Fair Value sits above the current price, based on confidence that recent margin repair and cash generation can stick.
The argument leans on Main Street Pro customers, logistics rework, and private label to reshape earnings power. A buyer now effectively backs the idea that execution on those mix and efficiency moves continues without major stumbles.
"Bullish analysts expect Advance Auto Parts to translate its ongoing supply chain consolidation, merchandising work, and store operating model changes into structurally higher margins and stronger free cash flow over time. The main factor that has to go right is continued execution on the refocus toward higher margin Main Street Pro customers, along with completing supply chain and store productivity programs without further setbacks in DIY demand."
The price and this Narrative do not agree. → Uncover what this Narrative says Advance Auto Parts is actually worth
Where Could You Get There Earlier?
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 33% below our estimate - executes subsea projects using standardized kits and digital remote operations.
- Company 2 - 27% below our estimate - integrates data center hardware with proprietary software to accelerate artificial intelligence workloads.
- Company 3 - 30% below our estimate - develops ore bodies into longer-life mines through disciplined capital and operating plans.
That is three of the list. See the full list of 25 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com