
- AutoNation appointed Ravi Simhambhatla as Chief Technology and AI Officer on 1 October 2026, giving him responsibility for technology, data science, cybersecurity, AI and digital product development across the group.
- His track record across Avis Budget Group, Google Cloud, Tesla and several airlines indicates a push for deeper digitalization of AutoNation’s retail, fleet and customer experience platforms.
- We will now see how AutoNation's investment narrative could shift as Ravi Simhambhatla takes charge of its technology and AI roadmap.
Scan how AutoNation’s tech-focused hire fits into a wider shift toward AI heavy business models by reviewing the hand picked 92 AI infrastructure stocks shaping the next wave of automation.
AutoNation Investment Narrative Recap
To own AutoNation, you need to believe the higher margin aftersales and finance engine can keep doing the heavy lifting while new vehicle volatility and EV softness stay manageable. In the near term, the story still revolves around customer financial services and the parts and service footprint, not this hiring headline.
The new Chief Technology and AI Officer appointment mostly supports existing priorities rather than creating a new short term catalyst. The bigger swing factor remains execution on AutoNation Finance and protecting aftersales volume if customers defer maintenance or if repair work shifts to over the air fixes. Regulatory scrutiny of dealer practices also stays on the front burner.
Among recent developments, the build out of AutoNation Finance looks most connected to this technology hire. A US$2.67b loan book, 18% penetration of financed sales and US$11m in quarterly profit put real weight on this platform and on the systems that price risk, service loans and handle collections.
Ravi Simhambhatla’s remit over data science, AI and cybersecurity plugs directly into those operational needs. Tighter underwriting tools, smoother digital onboarding and more automated collections could all affect unit economics and credit outcomes. For you as a shareholder, the investment case now leans even more on whether management executes cleanly on this finance led, tech heavy model.
What The Current Analyst Setup Implies For AutoNation
AutoNation's narrative projects US$31.4b revenue and US$833.6m earnings by 2029. That profile lines up with analysts building in 4.6% yearly revenue growth and an earnings increase of about US$58.9m from US$774.7m today.
Uncover why AutoNation's fair value indicates a 55% potential upside to its current price, which could narrow quickly.
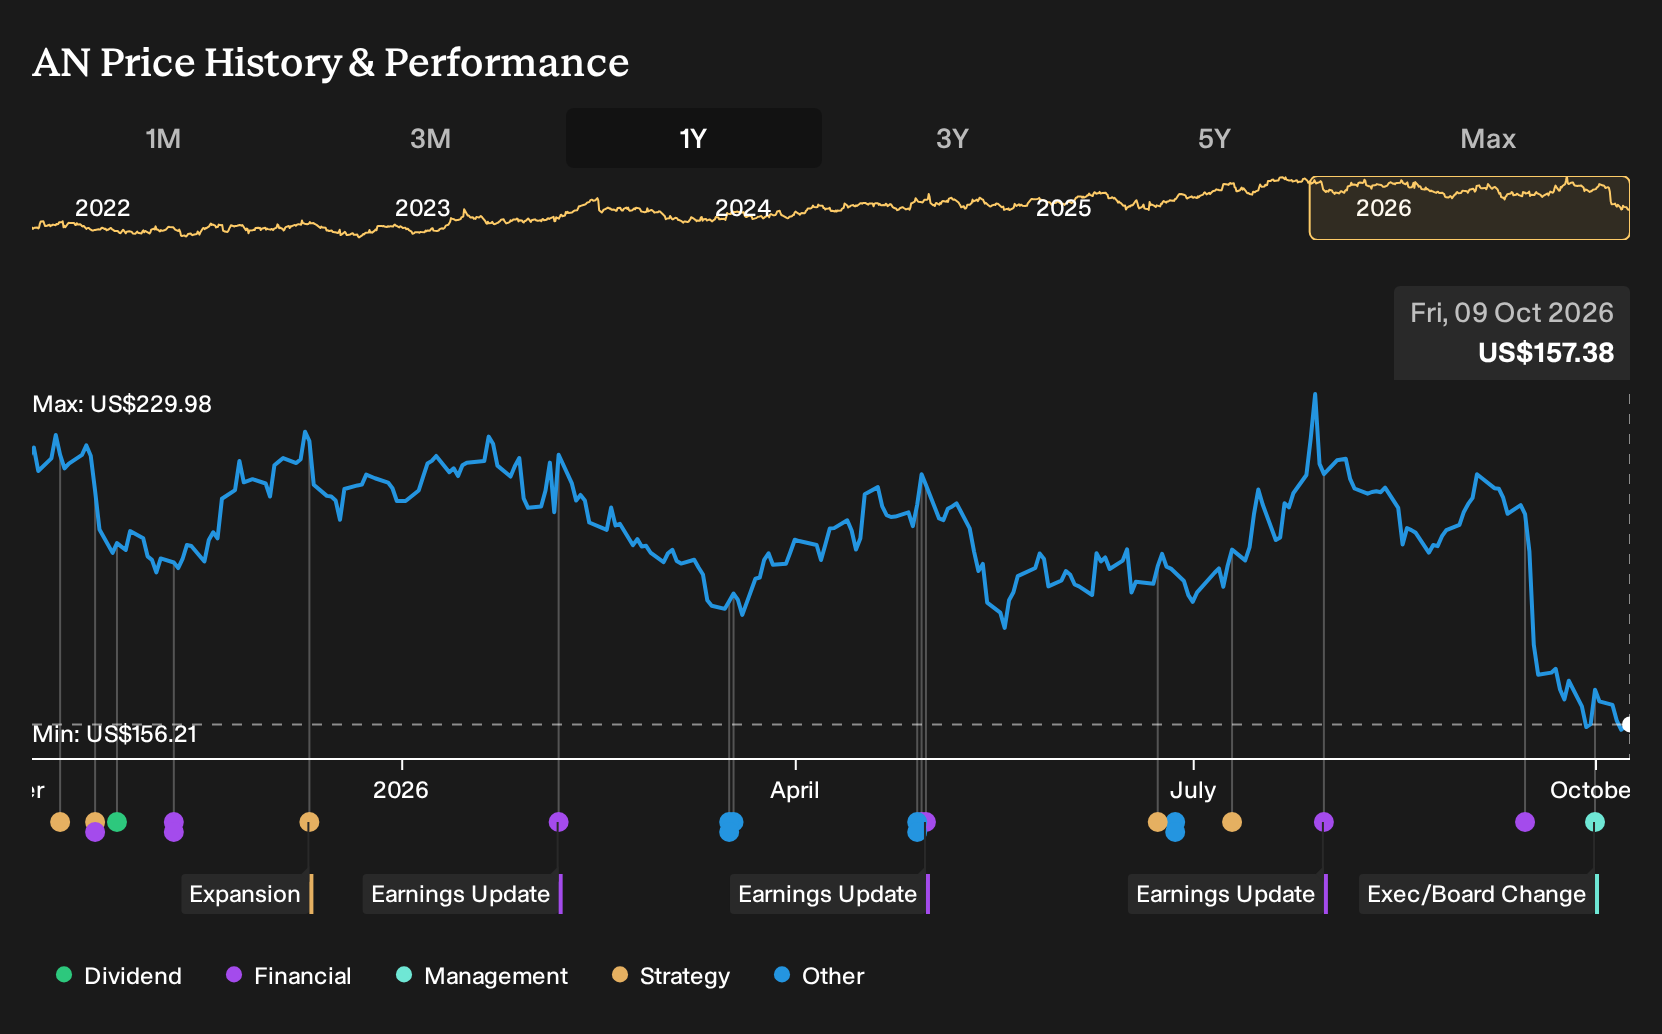
Exploring Other Perspectives
You are seeing one clear swing factor debated. Bullish analysts focus on AutoNation’s ability to expand high margin aftersales and finance profit, with revenue projections around US$31.6b and earnings near US$881.5m by 2029, compared with the consensus US$31.4b and US$833.6m. Both views pre date Ravi Simhambhatla’s hire, so opinions may evolve.
Explore another AutoNation fair value estimate, including one that suggests as much as 104% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AutoNation research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AutoNation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AutoNation's overall financial health at a glance.
Looking For More Investment Ideas Beyond AutoNation?
Once you have a view on AutoNation, it helps to line it up against a broader watchlist so you can judge risk and reward in context rather than in isolation.
- If you want potential growth with smaller market values, consider reviewing 12 elite penny stocks with strong financials that already show stronger financial foundations than many peers.
- For investors who prefer value and quality together, scan the 29 high quality undervalued stocks to see which businesses combine robust cash flows with more conservative pricing.
- If stability matters most to you, focus on capital preservation first by checking the 31 resilient stocks with low risk scores that score well on resilience and downside protection.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com