
SpaceX planning to raise US$40b in debt to buy Nvidia AI chips is a loud signal that the race to build AI infrastructure is accelerating, and the suppliers behind that spend are moving into the spotlight. Capital is flooding toward the picks and shovels of this new build out, and investors who ignore it risk watching from the sidelines. This article walks through three stocks tied to that SpaceX AI story and explains how the same news can shape your next move.
The three stocks highlighted below are just a sample. The same screen surfaced 72 more listed GPU and AI chip ecosystem suppliers with equally compelling, but very different, business stories that are not covered here.
If you want to move past headlines and start lining up your own highest conviction ideas, head straight into the Listed GPU and AI-Chip Ecosystem Suppliers screener to identify, compare, and analyze the companies that match your view of the AI infrastructure build out.
Soitec (ENXTPA:SOI)
Soitec plugs into this screener through the plumbing of AI hardware, supplying engineered wafers that sit underneath radios, edge AI chips, and data center optics. This positioning puts its core materials business squarely in the path of rising GPU and accelerator spending.
Soitec generates all its €592 million of revenue from its Electronics segment, selling specialized semiconductor substrates into mobile communications, automotive, industrial, edge AI, and cloud AI infrastructure markets. The stock carries a market value of about €5.7b.
"The ongoing large-scale transition to AI, data center expansion, and proliferating connected devices (including IoT) is driving robust and accelerating demand for advanced substrates like those Soitec produces, supporting long-term revenue visibility and potential 2x revenue opportunity as their addressable market is projected to grow from 5 million wafers in 2024 to 12 million by 2030."
What happens to Soitec’s margins if that demand materializes while one quiet constraint on how quickly new capacity can be absorbed starts to bite?
If that constraint on absorption speed has you curious, the full narrative for Soitec breaks down how Soitec’s wafer demand, capital intensity and margin risk could be decoupling.

SICC (SHSE:688234)
SICC Co., Ltd. makes silicon carbide substrate materials that help power energy efficient chips for AI data centers and high performance electronics, tying it directly into the GPU and AI chip infrastructure theme. All CN¥1.6b of revenue comes from Semiconductor Material, and the stock is valued at about CN¥44.7b.
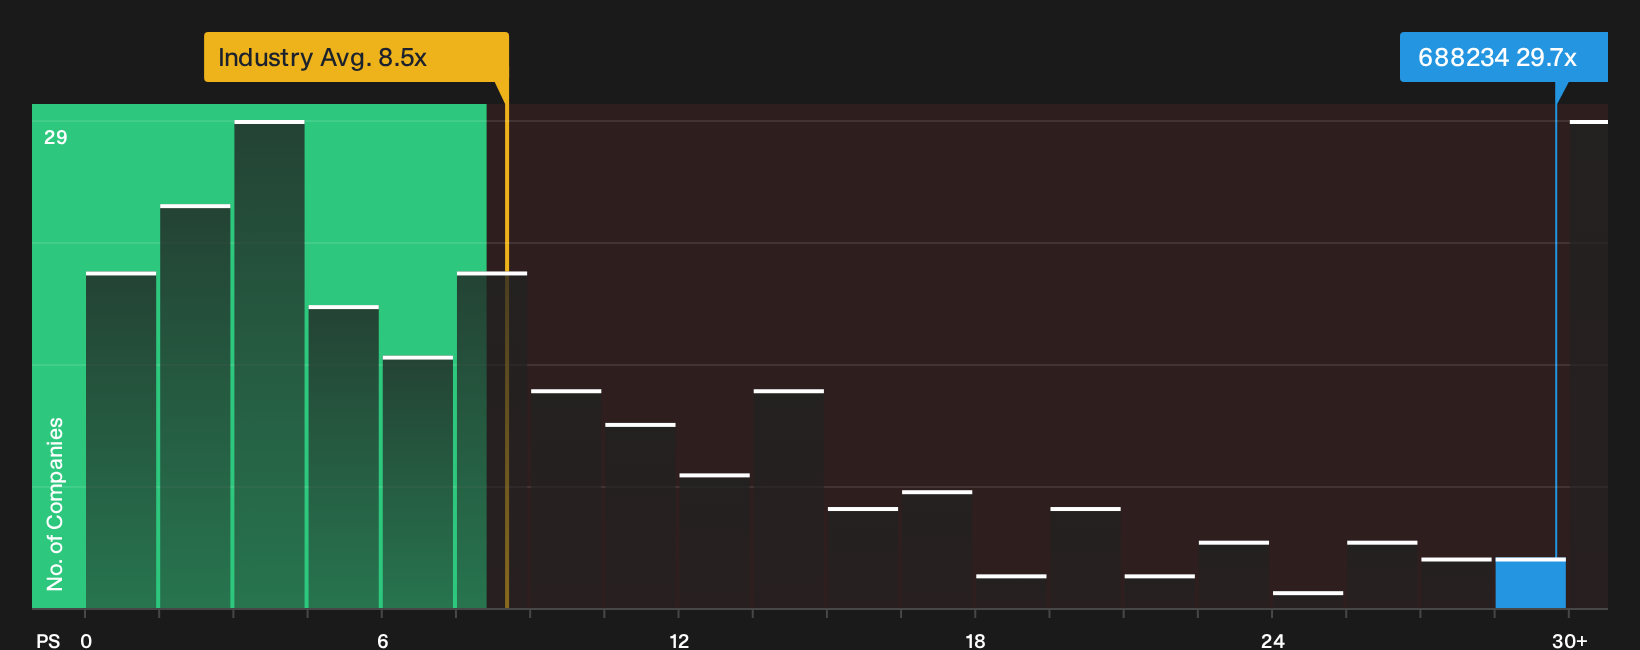
SICC provides focused exposure to silicon carbide wafers that support power hungry AI servers. The stock trades on a 29.7x P/S while still loss making and relying fully on external funding, so any change in how investors value that potential growth could have a significant impact.
That kind of rich P/S only matters if you understand the risk-reward equation behind it, so tap into the 1 key reward and 1 important warning sign for insight into what the multiple might be pricing in.
Onto Innovation (ONTO)
Onto Innovation is one of the purest ways to tap into the AI-chip build out, providing the inspection and metrology gear that keeps advanced GPU and accelerator production on track at leading foundries.
Onto Innovation generates about US$1.1b of revenue from Semiconductor Equipment and Services, supplying process control tools and software that support chip fabrication and advanced packaging, and the stock carries a roughly US$14.5b market value.
"The company’s Dragonfly platform recently passed TSMC’s New Tool Selection Committee qualification process for 2.5D advanced packaging applications. This is a significant milestone that could materially expand Onto’s role in the semiconductor ecosystem over the next several years. If packaging demand growth slows or customer ramps are delayed, valuation expectations could compress sharply."
What happens to Onto Innovation’s earnings profile if a single pressure point in that AI packaging build out shifts faster than the market expects.
If that pressure point worries you, read the full narrative for Onto Innovation to see how Onto Innovation’s AI packaging exposure could accelerate upside while masking real execution risk.

Seeking Fresh Alternatives Before They Fly
New themes are breaking out while early momentum is still under the radar for now. Scan these fresh lists before the crowd catches on and consider getting in at an earlier stage.
- Spot under-the-radar compounders with resilient cash flows by running the 179 high quality undervalued stocks while valuations still reflect old assumptions rather than recent momentum.
- Track the next wave of automation beneficiaries by scanning the 91 robotics and automation stocks before capital flows re-rate these operators and entry points begin to shift.
- Review potential opportunities in a possible grid upgrade cycle by using the curated 43 power grid technology and infrastructure stocks while these infrastructure players are still less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com