
General Mills (GIS) just wrapped up a series of cash tender offers for several long dated senior notes, a balance sheet move that can influence future interest costs and debt structure.
Recent moves on debt and governance come against a weak trading backdrop, with General Mills’ share price down 29.37% year to date and its 1 year total shareholder return declining 31.35%. This indicates pressure has been building for some time, despite a small 7 day share price gain of 0.87% and an 11.78% fall over 90 days.
Compare General Mills’ debt clean up with other companies tightening their balance sheets by scanning the list of solid balance sheet and fundamentals (25 results) for potential ideas in the same direction.
General Mills is trimming long dated debt while the share price has already taken a heavy hit. Does that cleanup leave more upside than downside risk from here once you line it up against valuation?
Most Popular Narrative: 14.3% Undervalued
Based on the most followed narrative, General Mills is valued at a fair value of $37.67 compared with the last close at $32.29. This frames the tender offers against a market view that already embeds long term cash flow expectations.
General Mills plans to deliver US$750 million of cost savings in fiscal 2027 as part of a US$3 billion program through fiscal 2030, which could support net margins and earnings as Holistic Margin Management and broader efficiencies scale.
See why 97 investors see General Mills as 14% undervalued.
Result: Fair Value of $37.67 (UNDERVALUED)
Still, weak recent earnings trends and the Pillsbury product recall risk show how execution or quality issues could quickly challenge the current General Mills narrative.
Find out about the key risks to this General Mills narrative.
Another View: What Multiples Say About General Mills
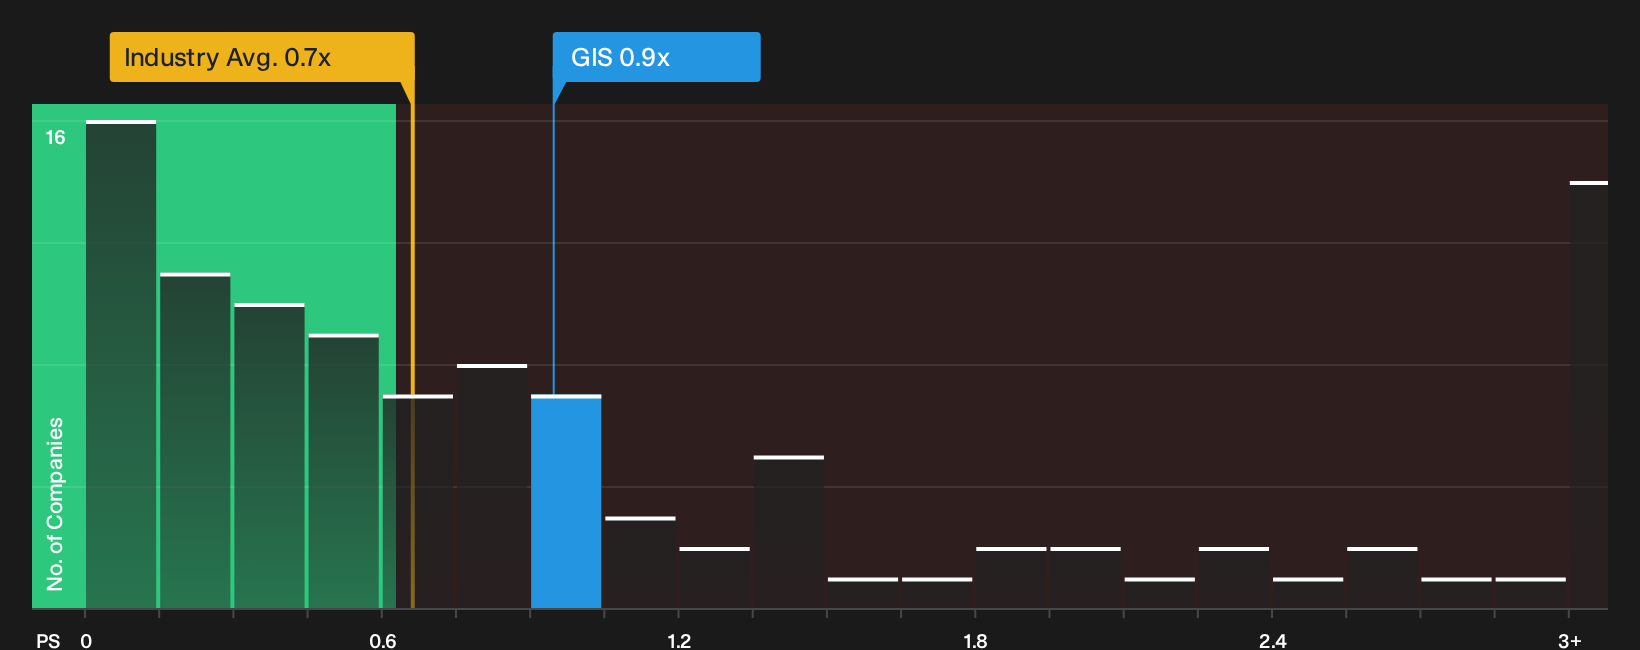
The SWS fair value and analyst narrative both point to General Mills looking undervalued on long term cash flows. Yet the P/S ratio tells a different story. At 0.9x sales, the stock trades above both peers and the wider US Food industry at 0.7x.
The fair ratio sits at 1x, so current pricing is below that reference point but still richer than the sector. That mix suggests less of a clear bargain and more of a trade off between potential upside and the risk that the market keeps aligning GIS closer to its industry multiples.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between cost cuts, recalls and valuation signals around General Mills? Act while the data is fresh and test your own thesis by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond General Mills?
If General Mills has sharpened your focus on valuation and risk, use that momentum and widen your watchlist with a few targeted stock shortlists.
- Target dependable compounding by reviewing steady cash generators and balance sheet strength through the 29 high quality undervalued stocks.
- Hunt for resilient performers with defensive qualities by scanning the 31 resilient stocks with low risk scores that filters for sturdier financial profiles.
- Spot tomorrow’s potential standouts early by checking the 20 high quality undiscovered gems before the wider market pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com