
Lamb Weston Holdings (LW) just packed several developments into one day, including a leadership transition for its International president, fresh quarterly earnings, updated 2027 sales guidance, a confirmed dividend, and a completed multi year buyback.
Short term traders have seen Lamb Weston Holdings swing around this news, with a 1 day share price return of 3.21% decline after a 7 day share price gain of 9.79%. The 1 year total shareholder return is down 22.59%, which points to fading longer term momentum despite the recent bounce.
Spot shifts like Lamb Weston Holdings is facing and scan a hand picked 29 high quality undervalued stocks with solid cash flows and balance sheets that may be priced below their fundamentals.
Lamb Weston Holdings still looks like a solid frozen potato business on paper, yet the share price slide and recent rebound raise a sharper question: Is this a quality producer trading at a fair tag or a discount?
Most Popular Narrative: 40% Undervalued
Lamb Weston Holdings closed at $47.87, while the most followed narrative puts fair value at $48.06, which implies a very small absolute gap but a 40% discount to that estimate when expressed as a percentage of perceived intrinsic worth. For a stock that has seen a sharp pullback over the past year, that framing makes the recent rebound look more like a catch up move than froth.
TheGapReport: Lamb Weston Holdings, Inc. (NYSE:LW) Q1 2027 (jul 24 to oct 6) Lamb Weston opens fiscal 2027 with a first quarter that beat its own guidance on nearly every headline line, and the October 6 call is built to make that beat the story. The more useful question is what became of the commitments management made in July, when it still asked investors to wait for the international segment to turn. Delivered The clearest test is the first-quarter guide. Management said it expected net sales to be flat and adjusted EBITDA to decline in the low teens. The call reports net sales up 1% and adjusted EBITDA of $286 million, down 5%, which Jim Gray describes as “substantially better than our expectations.” The delivery is real. The yardstick is what has moved. Jan Craps presents the quarter as one where the company “over-delivered our Q1 expectations,” measuring it against the expectations set in July. Mike Smith uses the more neutral phrase “above our guidance.”
See why 2 investors see Lamb Weston Holdings as 0% undervalued.
Result: Fair Value of $48.06 (UNDERVALUED)
Still, Lamb Weston Holdings relies heavily on North America volume strength and an international reset, so any stumble in contracting or overseas execution could quickly weaken that undervalued story.
Find out about the key risks to this Lamb Weston Holdings narrative.
Another View: Lamb Weston Holdings Through Earnings Multiples
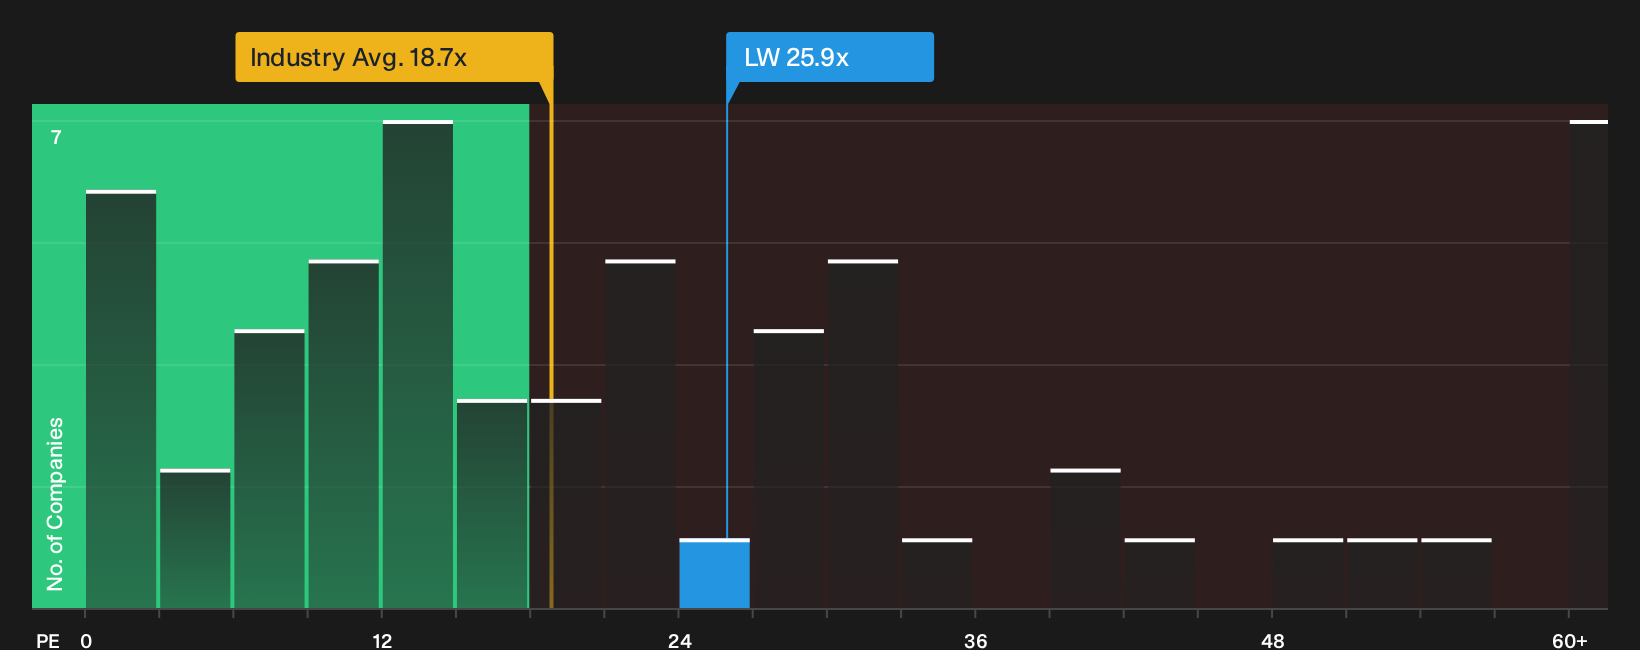
The story changes once you look at Lamb Weston Holdings through its P/E. The stock trades at 25.9x earnings while peers sit closer to 16.2x and the US Food industry around 18.7x. The fair ratio points to 21.3x, which suggests investors are already paying up for the current earnings profile.
A richer multiple can sometimes signal confidence, but it also narrows the margin for error if earnings or margins do not track expectations. That mix leaves a simple question for holders to ask themselves: Is this premium tag a comfort or a risk if the thaw in sentiment does not last?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Lamb Weston Holdings is split, with clear concerns sitting right beside genuine optimism about what could go right next. If you want to move quickly and ground your own view in the underlying data rather than headlines, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lamb Weston Holdings?
If the Lamb Weston Holdings story has you rethinking your watchlist, use this moment to refresh your ideas and line up your next potential moves.
- Target dependable cash flows and balance sheets by reviewing the list of solid balance sheet and fundamentals (25 results) that may hold up when conditions get tougher.
- Hunt for potential mispricing by scanning a 20 high quality undiscovered gems that the market might not be paying full attention to yet.
- Dial back portfolio stress by focusing on a 31 resilient stocks with low risk scores that leans toward resilience over drama.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com