
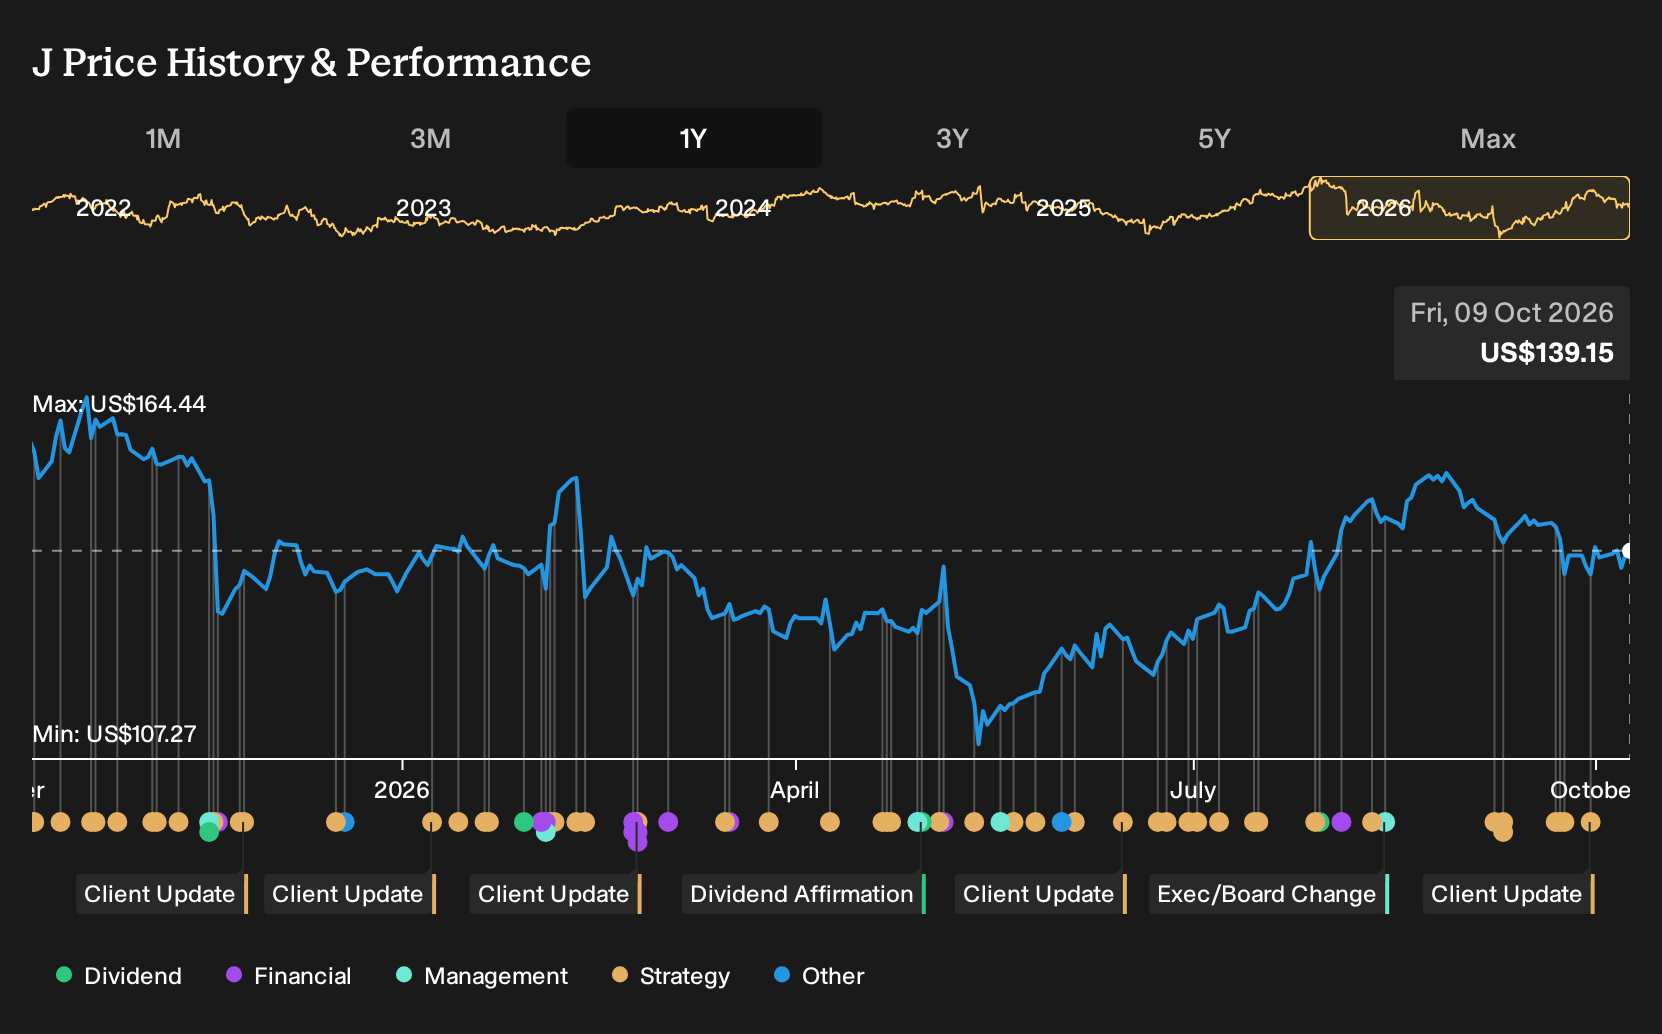
- On 30 September 2026, NVIDIA selected Jacobs Solutions to deploy its Data Center Digital Twin under a three year SaaS agreement for a large US AI R&D facility, integrating engineering models, operational technology and live data to support forecasting, leak detection, maintenance and operator training.
- The win underscores how Jacobs Solutions is building a software based role inside AI heavy infrastructure, where digital twins can influence power usage, cooling efficiency and long term facility operating costs for hyperscale clients.
- We will now look at how Jacobs Solutions' investment narrative is influenced by this NVIDIA digital twin contract and long term SaaS exposure.
Scan how Jacobs Solutions stacks up in AI infrastructure by comparing it with hand picked 92 AI infrastructure stocks building and operating the data centers behind today’s largest workloads.
Jacobs Solutions Investment Narrative Recap
To own Jacobs Solutions, you need to believe the business can keep turning a record US$29b backlog, growing AI related work and critical infrastructure demand into steadier earnings and better margins, despite recent pressure on net profit margins and a high P/E. The NVIDIA digital twin deal fits that story, but it is one contract inside a much larger portfolio.
The near term swing factor still looks like execution on large, multi year AI data center and infrastructure programs converting into higher quality earnings and cash flow. The biggest risk remains exposure to government and public sector budgets and the possibility that AI related awards prove more short cycle than current expectations.
The NVIDIA agreement matters most because AI data centers already account for about 11% of adjusted net revenue, with management pointing to a data center pipeline that is roughly 3x to 4x prior levels over the next few years. This contract shows Jacobs Solutions is not just designing facilities, but also supplying recurring software and digital operations tooling.
If similar deployments scale across more sites or clients, that could deepen relationships with hyperscale customers and reinforce the multi year revenue conversion thesis embedded in the US$29b backlog. The risk is that investors will watch closely to see whether this kind of SaaS heavy work smooths earnings or adds another source of volatility if large AI projects pause or shift timing.
Jacobs Solutions' narrative projects US$17.5b revenue and US$1.2b earnings by 2029. This implies 7.1% yearly revenue growth and roughly a 3.3x increase in earnings from US$359.3m today.
Uncover why Jacobs Solutions' fair value indicates a 17% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four retail investors in the Simply Wall St Community currently peg fair value for Jacobs Solutions between US$110 and about US$273, a wide spread that signals sharply different expectations. You can weigh those views against risks around public sector budgets and AI project timing, which could influence how that backlog turns into future earnings power.
Explore 3 other Jacobs Solutions fair value estimates, including one that suggests as much as 96% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Jacobs Solutions research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Jacobs Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jacobs Solutions' overall financial health at a glance.
Looking For More Ideas Beyond Jacobs Solutions?
Once you have a view on Jacobs Solutions, it can help to cross check that thesis against other opportunities that fit your preferences for value, quality or income. The Simply Wall St Screener is built for exactly that kind of side by side comparison.
- If you want a wider field of potential bargains with solid fundamentals, scan a curated 29 high quality undervalued stocks that already clear basic quality and valuation checks.
- If capital preservation and balance sheet strength matter most to you, filter for companies through a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses with sturdier financial footing.
- If you lean toward overlooked opportunities with room to gain attention, start with a hand picked pool of 20 high quality undiscovered gems that combine financial quality with lower current visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com