
- EPAM Systems launched a new AI-focused services offering in early October 2026 that provides high-fidelity data generation, rigorous model evaluation and custom reinforcement learning environments to help frontier AI models handle complex enterprise workflows more reliably.
- The new reinforcement learning environments are designed to simulate real enterprise systems in secure, closed-loop settings, which directly targets reliability, compliance and tooling needs for multi-step AI agents in regulated and mission critical workflows.
- We will look at how EPAM Systems' investment narrative is affected by this frontier AI workflow push and custom reinforcement learning environments.
Scan how EPAM Systems fits into the broader AI buildout and compare it with a hand-picked set of 92 AI infrastructure stocks powering these next-wave enterprise workloads.
EPAM Systems Investment Narrative Recap
To stay comfortable as a shareholder in EPAM Systems, you need to believe the shift toward AI native, consulting heavy work will steadily offset weakness in slower, task based projects, especially in North America where growth recently sat at 0.5% year over year. In the near term, the key upside catalyst is turning a growing AI revenue mix into more consistent bookings and maintaining recent non GAAP operating margins of 16.4%.
The biggest risk is that softer client decision making, macro pressure and internal go to market issues in North America keep organic constant currency growth near the 2% to 3% guidance range. Extended free cash flow pressure, after losses of US$54 million in Q1 2026 and US$18 million in Q2 2026, would make it harder for EPAM Systems to support capital returns even if accounting earnings improve.
The new frontier AI services launch matters because it focuses on what is already working inside EPAM Systems. AI native work contributes more than 11% of revenue and has recorded six straight quarters of double digit sequential growth, and the new high fidelity data and reinforcement learning environments directly target complex, multistep workflows that sit behind larger deal sizes.
Gartner expects almost all agent platform providers to offer simulation environments by 2028, up from less than 25% in 2026. EPAM Systems is positioning its offering in an area where industry coverage is still relatively low but expected to become standard. Execution risk is material, especially around monetizing these environments and converting a pipeline of roughly 10 large AI led, vendor consolidation and managed services deals into multiyear contracts from early 2027, yet the announcement remains aligned with those stated catalysts.
EPAM Systems' analyst narrative points to forecast revenues of US$6.3b and earnings of US$539.8m by 2029, based on an assumed 4.1% yearly revenue growth rate and consensus earnings that rise by about US$138.1m from current earnings of US$401.7m.
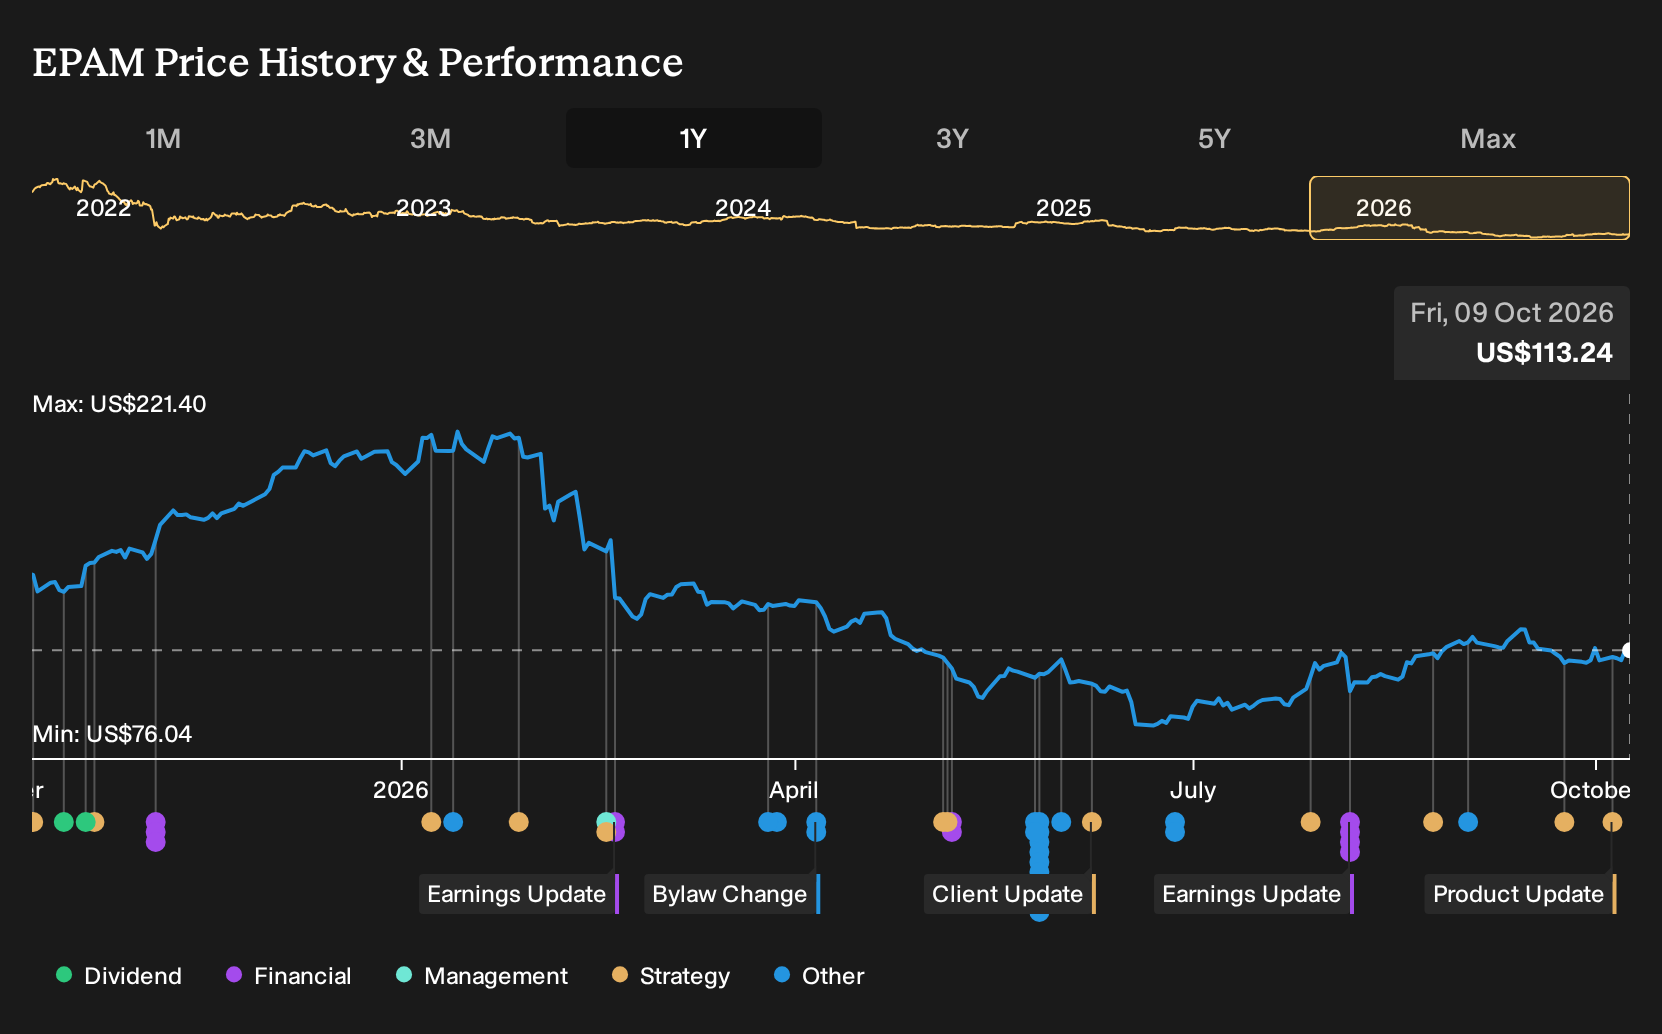
Uncover why EPAM Systems' fair value indicates an 8% potential upside to its current price. This opportunity could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts were already assuming EPAM Systems could reach about US$6.4b in revenue and US$602.2m in earnings by 2029, largely on a stronger North American reset. You now have this new frontier AI workflow offering on top. Those earlier forecasts did not factor it in, so expectations could shift meaningfully.
Explore 6 other EPAM Systems fair value estimates, including one that suggests there could be as much as 102% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your EPAM Systems research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for EPAM Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EPAM Systems' overall financial health at a glance.
Looking For More EPAM Systems Sized Ideas?
If the EPAM Systems story has you rethinking where AI heavy workflows might create long run edge, it can help to scan a wider field of companies with different risk and return profiles.
- If capital preservation is the priority, filter for steadier business models using a 31 resilient stocks with low risk scores that screens for resilience before excitement.
- If balance sheet strength matters most, start with a list of solid balance sheet and fundamentals (25 results) that surfaces companies with cleaner leverage and funding profiles.
- If you want to spot potential outliers early, cast a wider net across a 20 high quality undiscovered gems that focuses on quality metrics rather than headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com