
- AT&T recently detailed several moves, including offering the new iPhone Duo and iPhone 18 line on its network with sizable trade in credits, and forming fiber and satellite focused joint ventures aimed at broadening coverage and wholesale reach across underserved U.S. communities.
- The key twist for investors is that these expansion efforts arrive just as SpaceX commits US$8b to a nationwide wireless spectrum portfolio, which sharpens questions about how AT&T balances heavy network investment, device subsidies and new competition for future recurring service revenue.
- Now the focus shifts to how AT&T's investment narrative holds up against SpaceX's spectrum move and what that means for investors.
Compare how AT&T's connectivity push stacks up against other carriers by scanning 43 power grid technology and infrastructure stocks to see how it is shaping the next leg of network infrastructure and coverage expansion.
AT&T Investment Narrative Recap
To own AT&T, you need to believe the heavy bet on fiber, 5G and converged plans will keep service revenue resilient even as earnings are forecast to edge lower over the next few years. The latest spectrum news around SpaceX puts more attention on how effectively AT&T can monetize its large network footprint.
In the near term, the key swing factor is whether recurring service revenue and customer lifetime value stay strong enough to justify aggressive device credits on premium iPhones. The main operational risk is that subsidies and high debt costs squeeze margins and free cash flow before copper cost reductions fully land.
The iPhone Duo launch and refreshed iPhone 18 line sit right in the middle of that trade off. AT&T is offering up to US$1,200 in trade in credits, up to US$800 to pay off a rival device balance and online savings per line, all designed to bring more accounts onto Unlimited Your Way and Next Up Anytime.
For you as an investor, the question is whether those richer offers convert into higher value, stickier relationships across both wireless and fiber. If uptake of iPhone Duo and the new Pro models drives more converged households and keeps churn low, the promotion heavy quarter could support the catalyst of growing recurring service revenue while also testing the risk around equipment margin pressure.
AT&T's current analyst narrative points to revenues of US$137.1b and earnings of US$18.7b by 2029, based on 2.5% yearly revenue growth and an earnings decline of US$2.8b from US$21.5b today.
Uncover why AT&T's fair value indicates a 31% potential upside to its current price that could narrow quickly.
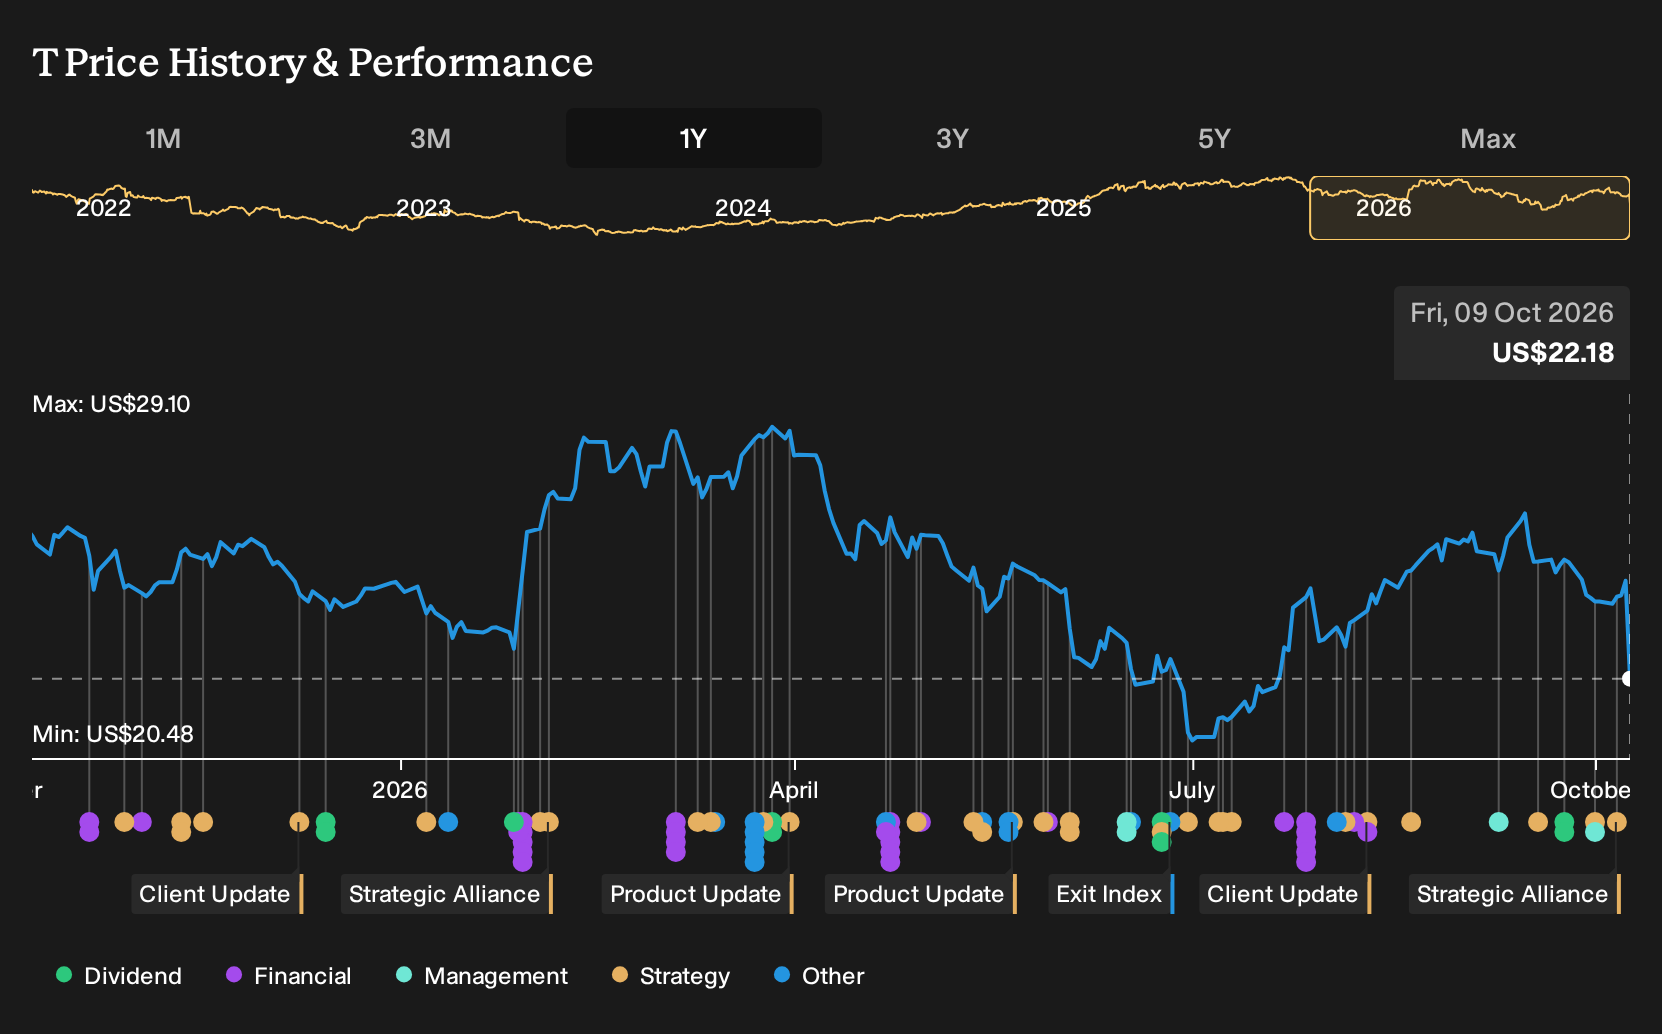
Exploring Other Perspectives
The most bearish analysts worry that AT&T’s heavy fiber and 5G push, now colliding with SpaceX’s US$8b spectrum move, could strain returns. They were penciling in only 1.8% annual revenue growth to about US$134.4b and earnings of US$17.2b by 2029. This is a much more cautious story that shows how sharply opinions can differ.
Explore 7 other AT&T fair value estimates, including one that suggests it could be worth just $21.74.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your AT&T research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for AT&T. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AT&T's overall financial health at a glance.
Looking For More Ideas Beyond AT&T?
If the AT&T story sharpened your thinking about risk, income and balance sheet strength, it can help to compare it with other businesses that line up with your own priorities.
- For investors who want a focus on financial resilience, review a list of solid balance sheet and fundamentals (25 results) that can help you zero in on companies with sturdier fundamentals.
- If your priority is finding potential value opportunities, scan a 30 high quality undervalued stocks that match strong business quality with prices that may not fully reflect it.
- Those who care most about income potential can assess 8 dividend fortresses that combine higher yields with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com