
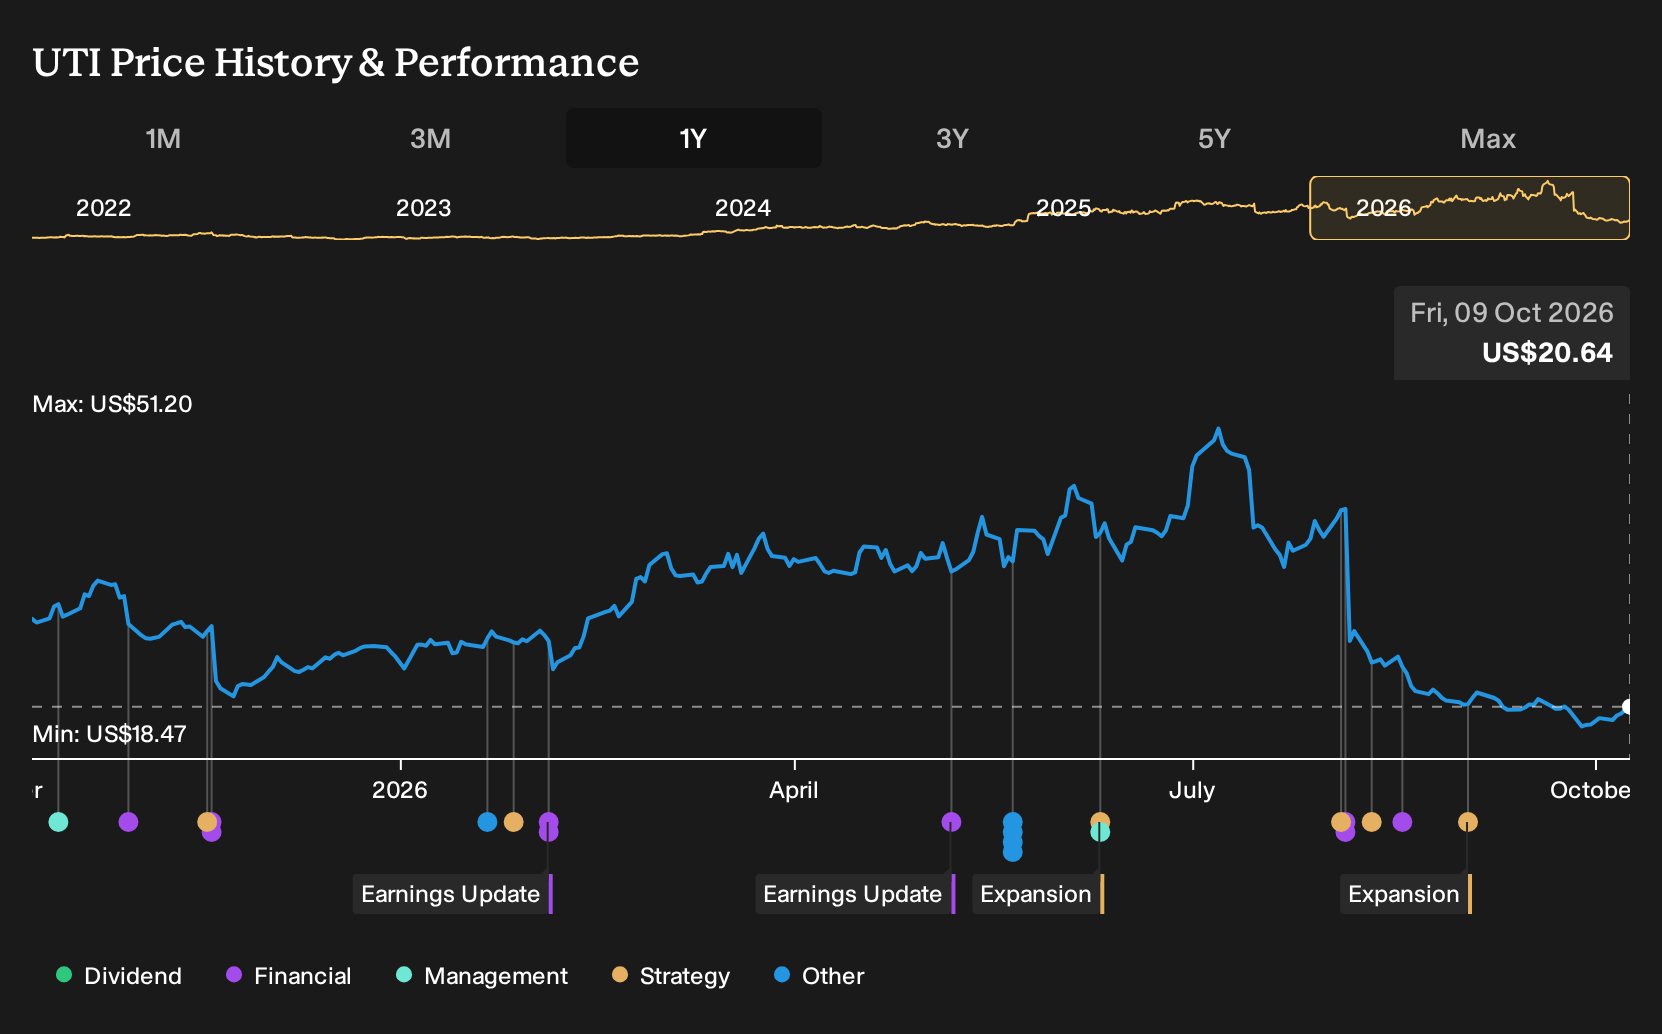
- Universal Technical Institute recently reduced its 2026 outlook as high school enrollments softened, while lifting Concorde Career Colleges growth limits to allow faster program launches and earlier campus additions.
- The same update highlighted how expanded Pell Grant eligibility for short-term credentials could reshape Universal Technical Institute’s mix toward shorter allied health and skilled trades offerings.
- The focus will now shift to how this new emphasis on accelerated Concorde expansion could reshape Universal Technical Institute’s broader investment narrative.
Universal Technical Institute Investment Narrative Recap
To own Universal Technical Institute, you need to believe the business can steadily rebalance away from slower high school auto and diesel enrollments toward shorter skilled trades and allied health programs without losing profitability. The cut to the 2026 outlook underlines that this transition is not smooth. The near term catalyst is execution on the pivot to shorter programs while stabilizing enrollment trends.
The biggest current risk sits in expansion outpacing real demand. Management is leaning into faster Concorde growth through new campuses and programs, which raises the chance of overcapacity if enrollments disappoint or regulatory timing slips. If those new locations fill efficiently, the recent guidance reset could end up looking more like a timing issue than a structural break.
The update that lifted growth limits at Concorde Career Colleges is the clearest operational swing factor tied to this news. With restrictions removed, Universal Technical Institute now has room to launch more short term healthcare and skilled trades offerings earlier than planned, which aligns with the shift in student preference away from longer programs.
For you as an investor, the question is whether the organization can scale Concorde quickly without straining systems, driving up integration costs, or depressing returns on new campuses. Momentum in areas supported by expanded Pell Grant eligibility and employer partnerships will be important evidence that the accelerated rollout is translating into sustainable enrollment and a more resilient program mix.
Universal Technical Institute is modeled to reach about $1.2b in revenue and $91.1m in earnings by 2029, based on analyst projections that assume roughly 9.5% yearly top line growth and an earnings increase of about $56.8m from current earnings of $34.3m.
Uncover how Universal Technical Institute's fair value indicates an 88% potential upside to its current price that could narrow quickly if sentiment on Universal Technical Institute improves.
Exploring Other Perspectives
One bullish angle on Universal Technical Institute leans heavily on acquisitions. The most optimistic analysts were penciling in revenue growth of 10.3% a year and earnings of about $97.4 million by 2029 before this news. You can treat those forecasts as one possible path that may shift as the new outlook beds in.
Explore another Universal Technical Institute fair value estimate, including one that suggests as much as 88% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal Technical Institute research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Technical Institute. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Technical Institute's overall financial health at a glance.
Looking for more investment ideas beyond Universal Technical Institute?
If the Universal Technical Institute story has you thinking about portfolio balance and risk, it can help to scan a wider field of opportunities using the Simply Wall St Screener. You can filter for cash strength, income potential, or underappreciated quality and quickly see which businesses line up with your own risk and return preferences.
- If capital preservation is a priority, start by reviewing companies with stronger balance sheets through our 31 resilient stocks with low risk scores, which highlight businesses with more resilient profiles.
- If value appeals to you, check companies that combine quality fundamentals with pricing that screens as potentially cheap by running the 28 high quality undervalued stocks.
- If you like the idea of finding under-followed opportunities early, scan through the 20 high quality undiscovered gems for stocks with solid fundamentals that attract less market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com