
Synopsys (SNPS) recently formed expansive AI alliances with OpenAI and Amazon, and rolled out its AgentEngineer platform. Together, these moves coincided with the stock moving sharply higher over the past month.
Those AI alliances have landed at a moment when momentum in Synopsys shares has clearly picked up, with a 30-day share price return of 29.7% and a 90-day gain of 14.48%, while the 1-year total shareholder return of 16.19% and 5-year total shareholder return of 66.52% point to a much longer build in investor interest.
Scan beyond Synopsys and its AI alliances by reviewing a curated group of AI infrastructure beneficiaries in our 92 AI infrastructure stocks that are also drawing interest from this shift toward automated chip design.
Synopsys now trades near recent highs while sitting about 12% below the average analyst target and a similar gap to estimated intrinsic value. Is that cushion genuine value, or is it simply a reflection of lagging spreadsheets?
Most Popular Narrative: 10.5% Undervalued
Against the latest fair value estimate of $569.78, Synopsys at $509.99 screens as discounted, and that gap rests on a very specific growth and margin story.
The ongoing transformation toward SaaS or cloud delivered and AI enabled EDA, including early traction in agentic AI with more than 20 to 30 customer engagements and evidence of up to 50x faster time to validated RTL and meaningful debug cycle time reductions, can increase tool usage intensity and support a mix shift toward subscription plus consumption models that may lift revenue visibility and earnings.
See why 166 investors see Synopsys as 10% undervalued.
Result: Fair Value of $569.78 (UNDERVALUED)
Still, this Synopsys story can break if the Ansys integration increases costs or if IP and China-exposed revenue underperform the AI-heavy expectations baked into the model.
Find out about the key risks to this Synopsys narrative.
Another View: Synopsys Through The Earnings Lens
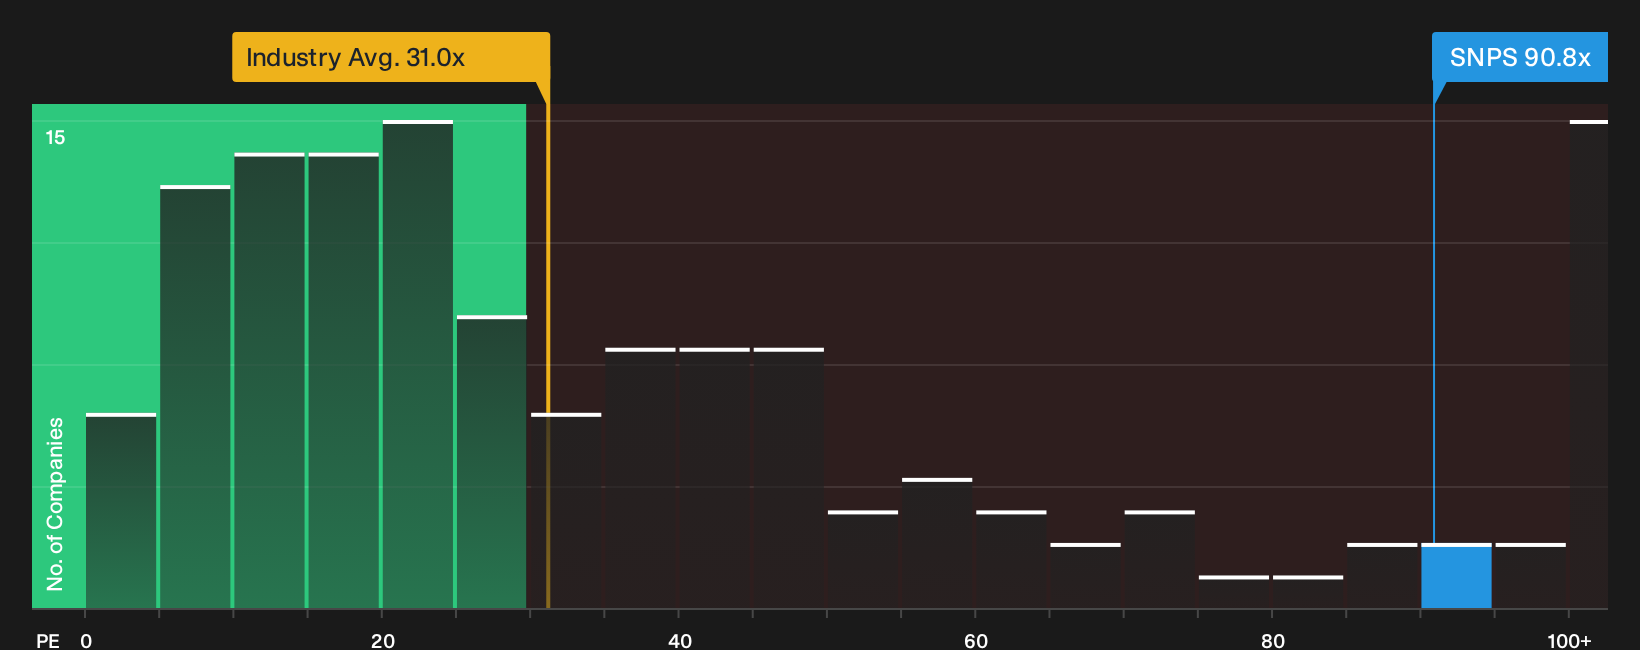
There is a very different read if you switch from fair value models to the plain P/E ratio. Synopsys trades on 90.8x earnings, compared with 31x for the wider US Software group and 34.3x for its peer set, and a fair ratio of 47.3x. That gap points to meaningful valuation risk if sentiment cools or forecasts are revised.
For a closer look at what that earnings multiple implies for Synopsys at today’s price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
All this leaves sentiment on Synopsys finely balanced, with both enthusiasm and concern on the table. Act while the data is fresh, carefully weigh the upside against the weak spots in the story, and use the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Synopsys?
If you stop with Synopsys, you miss the bigger opportunity set. Put a few minutes into scanning wider markets and you might surface your next key holding.
- Target resilient compounding potential with a 28 high quality undervalued stocks that combines stronger balance sheets with pricing that has not yet caught up to fundamentals.
- Protect your downside by focusing on stability first and use the 31 resilient stocks with low risk scores to filter for businesses with more resilient profiles.
- Hunt for tomorrow’s leaders before they are widely followed by checking the 20 high quality undiscovered gems that pair quality metrics with limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com