
- Reliance has seen its valuation stretched relative to Metals and Mining peers as its P/E multiple moves well above sector comparisons, drawing questions about whether current earnings support this pricing.
- The nomination of senior Reliance executive Dhanraj Nathwani to the Rajya Sabha has sharpened focus on how political access interacts with long term earnings power and corporate governance.
- We will look at how Reliance's investment narrative is tested by its premium valuation as political exposure intensifies around the business.
Pressure test Reliance's premium by lining it up against a curated 28 high quality undervalued stocks list that combines sturdier pricing with more grounded earnings multiples.
Reliance Investment Narrative Recap
To own Reliance today, you need to be comfortable that its premium P/E still lines up with an earnings stream tied to data centers, public infrastructure, power projects, aerospace and defense work. The near term positive swing factor is simple: non residential construction and government related programs need to keep volumes and processing activity firm.
The biggest operational risk right now is not the Rajya Sabha headline. It is still metal input volatility and tariff policy on aluminum and carbon. Political visibility around Reliance may raise governance questions at the margin, but it does not fundamentally change that pricing swings and LIFO expense remain the key earnings swing factors.
With no fresh operational announcements tied directly to this political move, the more interesting reference point is Reliance lifting full year 2026 LIFO expense guidance from US$100m to US$300m as carbon and aluminum costs shifted. That earlier update framed how sensitive reported gross margin is to input swings, even when demand looks solid.
Viewed against today’s richer P/E versus Metals and Mining peers, this earlier guidance change matters for catalysts. Investors are watching whether volume tied to data centers, infrastructure, semiconductors and defense can offset tariff related margin compression. The more political attention the group attracts, the more consistently that operational execution will likely need to show through the income statement.
Reliance Forecasts Put The Premium To Work
Reliance's narrative projects US$17.9b revenue and US$1.2b earnings by 2029. This assumes 4.2% yearly revenue growth and an earnings increase of about US$306m from US$893.8m today.
Uncover why Reliance's fair value indicates that revenue and earnings expectations are broadly in line with its current price.
Exploring Other Perspectives
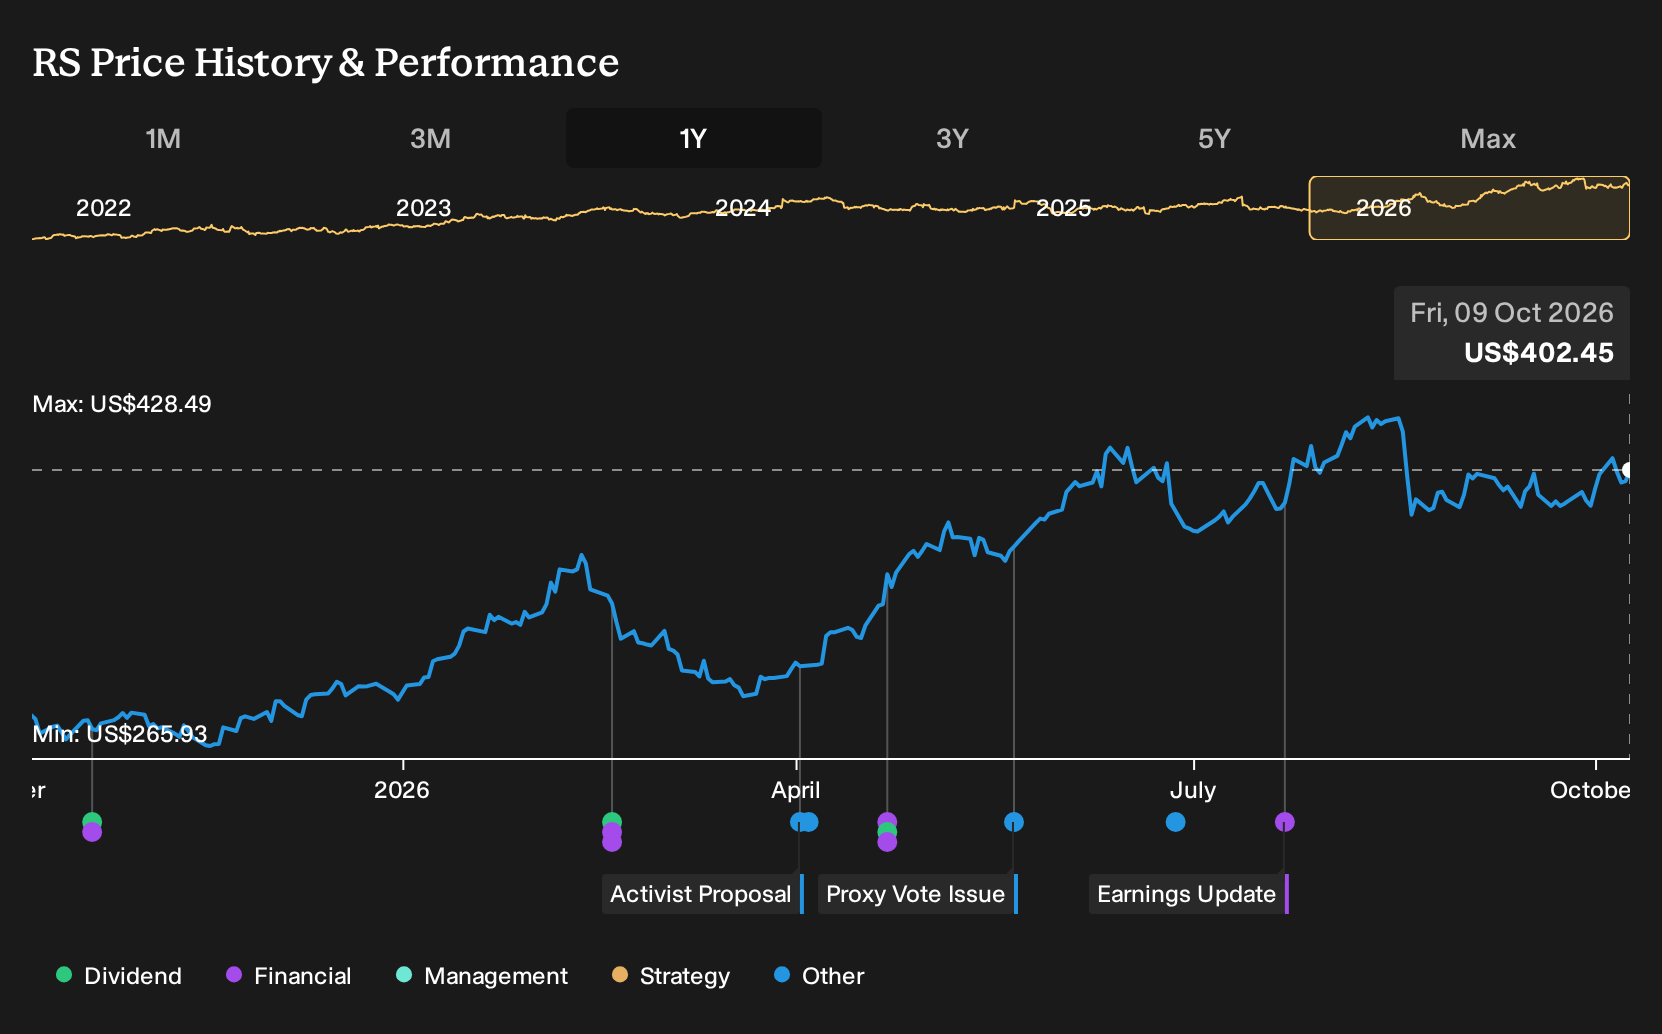
Two fair value estimates from the Simply Wall St Community range from about US$219.52 to US$408.88, which illustrates how far opinions on Reliance can differ. Those views do not yet factor in tariff risks or potential contract-driven catalysts. Use this as a prompt to compare multiple perspectives before deciding how Reliance fits your portfolio.
Explore another Reliance fair value estimate, including one that suggests it could be worth as much as $408.88.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Reliance research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Reliance. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Reliance's overall financial health at a glance.
Looking For More Investment Ideas Beyond Reliance?
Once you have a view on Reliance, it can help to cross check that stance against other opportunities that line up with your risk tolerance and income needs. The Simply Wall St Screener gives you a structured way to do that, so you are not relying on headlines or hunches alone.
- If capital preservation matters most, focus on sturdier balance sheets and steadier fundamentals through a list of solid balance sheet and fundamentals (25 results) that can act as the core of your watchlist.
- If you want income on top of potential price returns, scan for reliable payers with a 8 dividend fortresses that highlights companies offering higher yields with supporting financials.
- If you prefer backing under followed opportunities, hunt for less crowded ideas using a 20 high quality undiscovered gems that surfaces stocks with stronger fundamentals that are not widely tracked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com