
Aura Minerals (AUGO) drew fresh attention after reporting record preliminary Q3 2026 gold equivalent production, with output rising both year over year and quarter over quarter across its six operating mines.
The record Q3 production update arrived alongside a sharp move in Aura Minerals’ valuation, with the share price rising 10.63% in the last session to US$91.26. This contributed to a 90 day share price return of 50.07%, while the 1 year total shareholder return of 157.47% sits on top of a very large 3 year total shareholder return that suggests long running momentum has been building rather than fading.
Scan beyond Aura Minerals and see how other hand picked producers with strong recent momentum line up in our 36 elite gold producer stocks list.
Aura Minerals has surged on record production and a rapid re rating, yet the shares still trade below both analyst targets and some intrinsic value estimates. Where does a fair entry really sit in that spread?
Most Popular Narrative: 9% Undervalued
Aura Minerals closed at $91.26, while the most followed narrative pegs fair value near $99.96, so the story centers on whether current pricing fully reflects its mine pipeline, cash generation and capital returns.
The company’s strategy of disciplined greenfield build outs, ongoing exploration at Matupa, Carajás and Serra da Estrela and a pipeline of potential M&A in gold and copper positions Aura to become a materially larger producer over the next cycle. In a sector where scale commands higher price to net asset value ratios, this could lift the trading multiple and long term earnings, supporting share price appreciation.
See why 7 investors see Aura Minerals as 9% undervalued.
The narrative framework uses a discount rate of 8.96% to translate those future cash flows and earnings into today’s terms. This is a key reason it arrives at a fair value of about $100 rather than simply echoing the current share price. For you as a shareholder or prospective buyer, this gap between the market price and that estimate frames the recent production news and buyback activity as part of a bigger question about how much of Aura Minerals’ multi asset expansion and margin profile is already priced in.
Result: Fair Value of $99.96 (UNDERVALUED)
Still, the bullish Aura Minerals narrative can be knocked off course if gold and copper price assumptions reset lower, or if key projects like Borborema or MSG underperform expectations.
Find out about the key risks to this Aura Minerals narrative.
Another View: Aura Minerals Through the P/E Lens
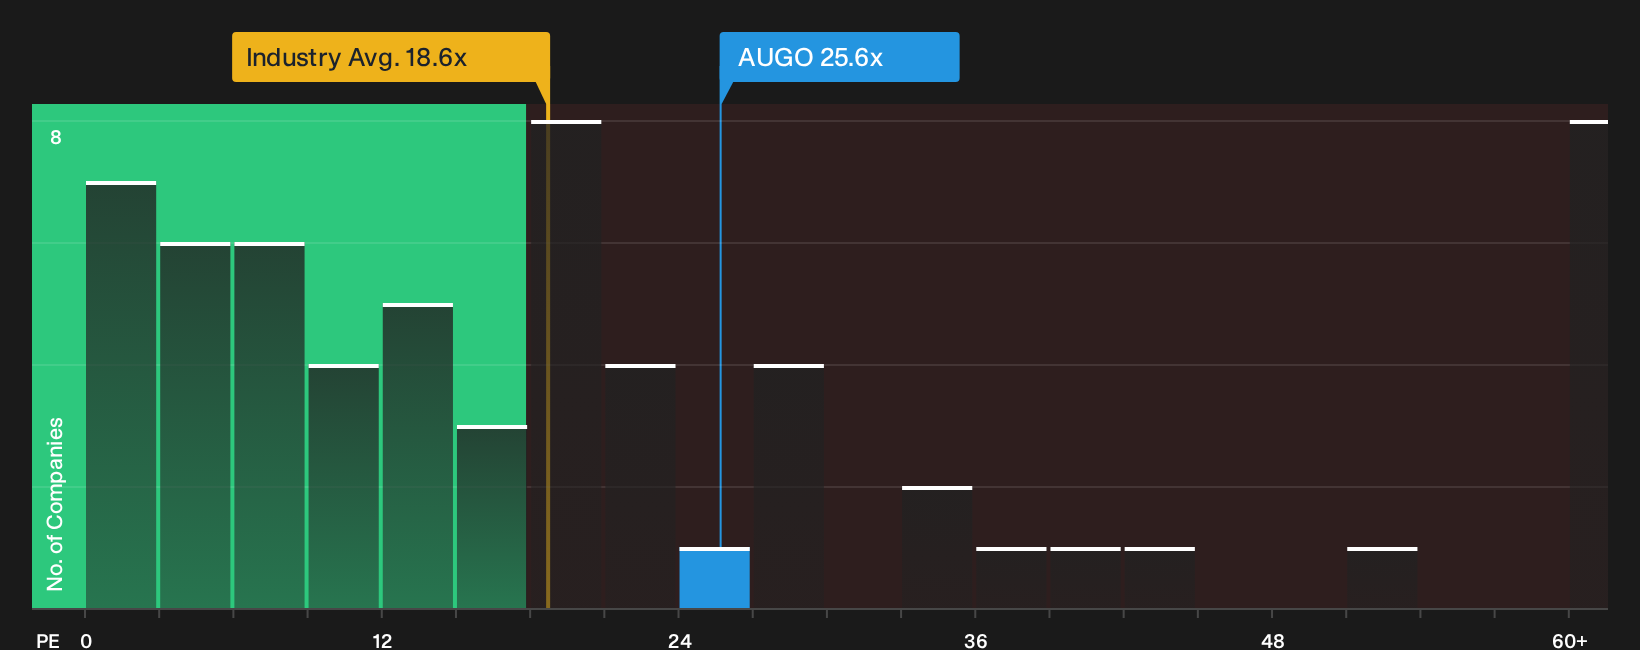
That fair value of $99.96 rests on future cash flows and analyst estimates. A simpler yardstick looks at Aura Minerals on its current P/E of 25.6x, which is higher than both the US Metals and Mining industry on 18.6x and the peer average on 17.2x, and only slightly below its fair ratio of 26.4x. For you, that points to a stock already priced at a premium on earnings, with less room for error if growth or margins fall short of expectations.
For a closer look at how this earnings based view could evolve as estimates shift, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Aura Minerals so far. If you want to move quickly and rely on your own judgment, start by weighing its 3 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Aura Minerals?
If Aura Minerals has your attention, broaden your opportunity set with a few focused stock ideas that match clear, disciplined checklists for quality and price.
- Target potential mispricing by reviewing our 28 high quality undervalued stocks that combine solid fundamentals with marked down market prices.
- Prioritize resilience and sleep better at night by scanning a 31 resilient stocks with low risk scores built around stronger balance sheets and steadier track records.
- Hunt for underfollowed opportunities by checking a 20 high quality undiscovered gems that highlight quality businesses still flying under most investors’ radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com