
- Timken recently reported Q2 revenue and EBITDA that were ahead of analyst expectations, which management framed as progress toward its plan to lift margins and support long term shareholder value.
- The stronger quarter landed against a backdrop of flat organic revenue over two years, softer return on invested capital and only modest EPS gains. This highlights the pressure on Timken’s Elevate to Outperform and 80/20 simplification program to improve the underlying business.
- We will now look at how Timken’s investment narrative could be affected by strong Q2 results alongside stagnant organic revenue trends.
Compare Timken’s mixed progress with a curated shortlist of industrial peers that are showing cleaner execution and stronger fundamentals in our list of solid balance sheet and fundamentals (25 results).
Timken Investment Narrative Recap
An investor in Timken needs to believe that the Elevate to Outperform and 80/20 programs can turn a flat organic revenue base into a higher margin, cleaner portfolio. The Q2 beat on revenue and EBITDA supports the idea that execution on cost, mix and simplification is progressing. The near term catalyst remains clear proof that these programs can lift margins without relying heavily on price.
The largest near term risk is that softer demand in areas like solar and wind, plus higher labor and equipment costs in aerospace and defense, keeps squeezing profitability as organic revenue stalls. Recent results do not remove that risk. They simply give Timken more credibility and time to show consistent operational improvement.
The most relevant context for the latest Q2 numbers is Timken’s ongoing Elevate to Outperform and 80/20 simplification push across its full revenue base. Management has tied this to a planned 500 bps uplift in adjusted EBITDA margin, helped by SKU and customer rationalization and stranded cost removal. A quarter that beats EBITDA expectations gives that effort some operational backing.
The same program links directly to other moving parts investors are watching, from exiting around US$150 million of lower return automotive OEM revenue to leaning harder into higher value Industrial Motion systems. The catalyst is not a single headline but whether Timken can keep reporting margins that reflect this portfolio shift while managing risks in solar, wind and aerospace cost inflation.
Timken analyst assumptions and valuation bridge
For Timken, the consensus blueprint is clear enough to model. Analysts are working off forecast revenue growth of 3.4% per year for the next three years, with profit margins rising from 5.4% today to 11.9% over that same period. On earnings, the group expects profits to move from US$258.7 million today to US$626.4 million, with a wide range of views that runs from US$528.5 million to US$730.4 million. That implies earnings would need to increase by about US$367.7 million from the current level to reach the 2029 consensus, which is a little over 2x the earnings base analysts are using today. The anchor year for these projections is 2029. This is also the period where the 80/20 and Elevate to Outperform work is assumed to be fully reflected in the income statement.
Timken's narrative projects US$5.3b revenue and US$626.4 million earnings by 2029, which analysts link to 3.4% yearly revenue growth and an earnings increase of about US$367.7 million from US$258.7 million today.
Uncover why Timken's fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
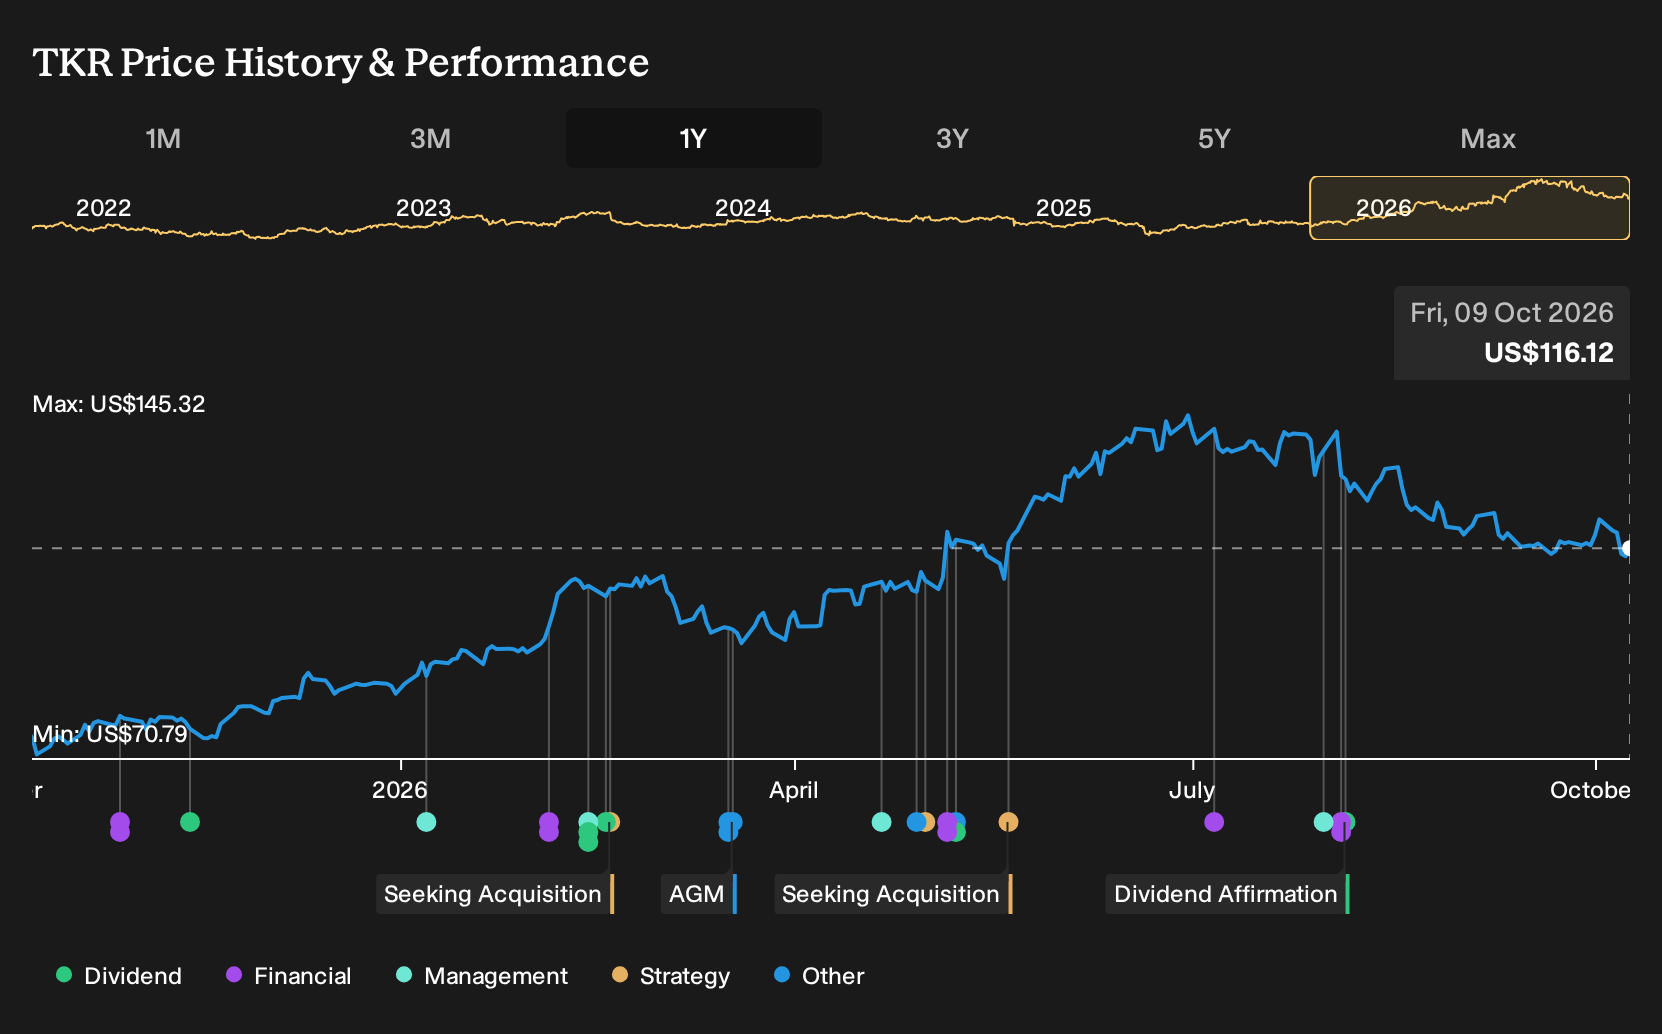
One alternative view focuses on cost pressure rather than margin uplift. The most cautious analysts were only penciling in about US$5.2b of 2029 revenue and US$525.9 million of earnings before this Q2 beat. That presents a much tougher Timken story. The sharp 18.2% share price drop suggests that these harsher assumptions might gain more attention, so treat this quarter as a prompt to compare both narratives, not the final word.
Explore 3 other Timken fair value estimates, including one that suggests as much as 22% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Timken research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Timken. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Timken's overall financial health at a glance.
Looking for more ideas beyond Timken?
If Timken has sharpened your focus on quality and execution, use that same lens to scan a broader watchlist. The Simply Wall St Screener lets you filter for the traits you care about most, then quickly compare fundamentals across a wide field of candidates.
- If you want financial strength and resilient balance sheets front and center, start with this curated list of solid balance sheet and fundamentals (25 results) that filters for sturdier fundamentals.
- If value is your priority and you prefer businesses that trade below what their quality might suggest, take a look at this focused set of 28 high quality undervalued stocks.
- If you are hunting for lesser known opportunities with solid underlying metrics, scan through this hand picked pool of 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com