
Watsco has seen its share price fall back over the past year, which naturally pushes investors to ask whether the current valuation lines up with what the business is earning. With the stock now trading at US$279.90, the key issue is how that price stacks up against the profits the company is already generating.
- The share price has declined 21.2% over the past year, which puts the spotlight firmly on whether the earnings can support where the stock now trades.
- The business model is closely tied to distributing heating and cooling equipment, so long term profitability may hinge on how efficiently it converts that activity into consistent earnings over time.
- There is a second opinion on Watsco worth weighing. See what analysts think Watsco's shares could be worth.
The stock's next move may depend on whether Watsco's current earnings are enough to justify the price investors are being asked to pay today.
If you want more ideas beyond Watsco while you weigh up its recent share price slide, a focused stock screen based on 28 high quality undervalued stocks can be a useful next research step.
Where Does Watsco Sit on Earnings?
P/E fits Watsco reasonably well because the business already reports earnings and investors can compare what they pay today with those profits.
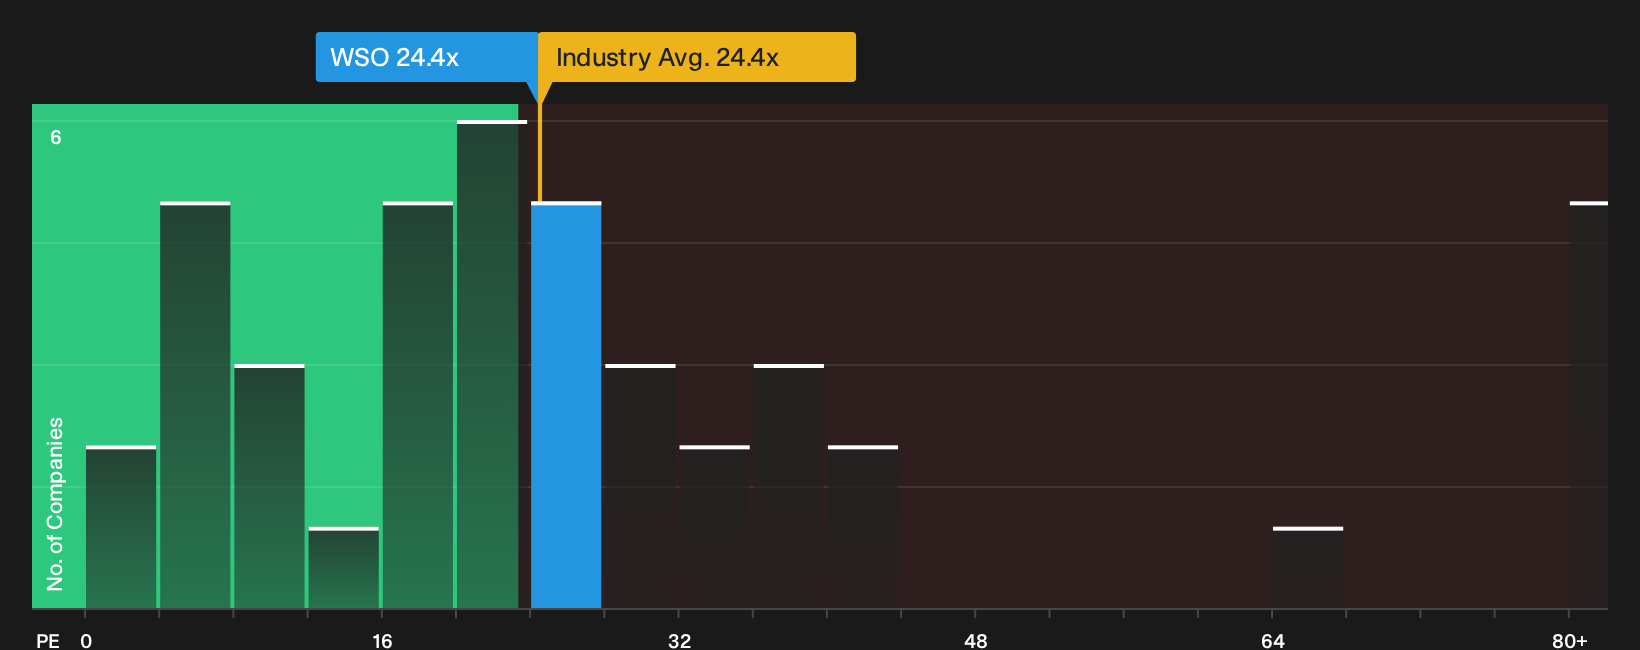
On that metric, Watsco trades at about 24.4x earnings. The broader Trade Distributors group sits around 24.4x, while the peer set is closer to 25.5x. A more tailored reference point for this ticker, which blends its sector, growth assumptions, margins, size and risk into a single yardstick, suggests the current P/E is close to what might be expected rather than sitting at a clear premium or discount.
For you as a shareholder or potential buyer, that means the 24.4x P/E neither clearly flags Watsco as overvalued nor obviously cheap based on this single lens. The more important question is whether the quality and resilience of its earnings line up with paying roughly in line with Trade Distributor peers on this measure. Explore the numbers behind Watsco's P/E valuation.
The Watsco Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the P/E puzzle around Watsco and spell out which future paths for growth, margins and earnings would need to hold for the stock to end up worth meaningfully more or less than today’s price, and they sit on the platform’s Community page. Each one turns Watsco's implied fair value into a clear, trackable hypothesis about the business so you can see how that view holds up over time.
One of the top community narratives on Watsco: 26% undervalued
The main thing that has to go right is that Watsco converts its heavy ongoing technology spend and growing e-commerce and OnCall Air usage…
Discover why this Narrative puts Watsco at 26% undervalued.
One valuation gap for Watsco that only the next few years can answer
Everything hinges on whether the earnings picture that analysts are sketching a few years out lines up with what you are paying for Watsco today. Explore where analysts expect Watsco to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com