
Freeport-McMoRan (FCX) just laid out its third quarter 2026 production picture, with copper output roughly matching expectations while gold volumes met guidance but included a shift of some Indonesian sales into the next quarter.
Freeport-McMoRan’s latest production update lands after a mixed stretch for the stock, with the share price up 15.64% over 90 days but down 7.15% over 30 days, while the 1-year total shareholder return of 66.02% points to momentum that has built over a longer horizon.
Spot 16 top copper producer stocks that echo Freeport-McMoRan's production story and could be setting up their own momentum shifts around upcoming operating updates.Freeport-McMoRan now trades at a discount to both analyst targets and some intrinsic value estimates after a choppy month-long pullback. Is that gap compensating you for the risks the market is flagging, or mispricing them?
Most Popular Freeport-McMoRan Narrative: 3% Undervalued
Freeport-McMoRan last closed at $71.14, while the most followed narrative pegs fair value around $73.14 using a 9.05% discount rate. That gap is small in price terms but backed by a detailed view on projects, margins, and copper exposure.
Freeport-McMoRan’s large above-ground copper stockpiles and progress with new leach additives and heated solutions, already producing around 200 million pounds per year with a target of 800 million pounds annually within 3 to 4 years, point to potential low incremental cost volume growth that could support higher future revenue and structurally lower unit net cash costs.
See why 108 investors see Freeport-McMoRan as 3% undervalued.
Result: Fair Value of $73.14 (UNDERVALUED)
Still, the Freeport-McMoRan story can flip quickly if Grasberg or the new Indonesian smelter hit fresh delays, or if project costs at Bagdad climb further.
Find out about the key risks to this Freeport-McMoRan narrative.
Another View: What Freeport-McMoRan’s P/E Is Telling You
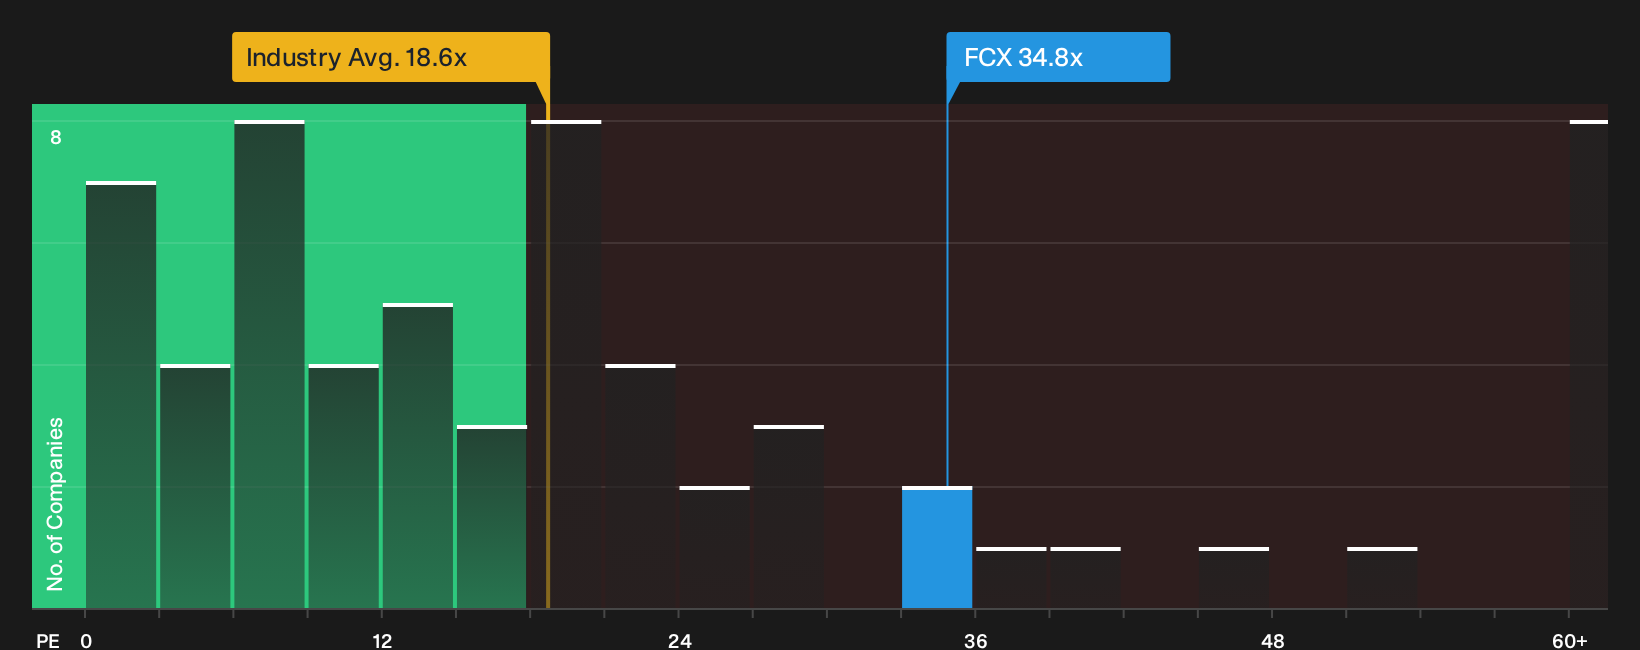
That 3% undervalued fair value story looks different once the focus shifts to earnings multiples. Freeport-McMoRan trades on a P/E of 34.8x, compared with 18.6x for the US Metals and Mining industry and 19.7x for peers, while the fair ratio sits lower again at 24.4x.
This gap points to real valuation risk if sentiment cools. The share price already assumes a richer earnings tag than sector and peer groups, plus a premium to the level the market could move toward over time. The key consideration is whether Freeport-McMoRan’s projects and copper exposure justify staying that far ahead.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Freeport-McMoRan is split, with both red flags and bright spots on the table. Move quickly, review the data, and let the full set of 2 key rewards and 1 important warning sign guide your own conclusion.
Looking for more investment ideas beyond Freeport-McMoRan?
If Freeport-McMoRan has you rethinking your portfolio, do not stop here. Fresh ideas often come from scanning outside your usual watchlist.
- Target reliable income streams by reviewing companies in the 8 dividend fortresses that could complement more cyclical exposure.
- Upgrade quality by focusing on balance sheets that can take a hit, starting with the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by scanning the 20 high quality undiscovered gems before everyone else starts talking about them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com