
Fresh attention on Ecolab (ECL) is coming from its High-Tech unit, where data center water treatment and AI server cooling, strengthened by the CoolIT acquisition, are emerging as key growth drivers.
That CoolIT deal and the push into data center cooling are landing in a period where momentum in Ecolab’s shares has been steady rather than explosive. The company has a 7.25% year to date share price return and a much stronger 75.55% three year total shareholder return, which hints that long term holders have seen the bigger payoff.
Scan beyond Ecolab’s high-tech push and see how other water and AI infrastructure plays stack up in the 92 AI infrastructure stocks.
Ecolab has already rewarded patient holders, yet a 75.55% three year total return and a recent push into high tech cooling leave a live question: Is most of the value already priced in, or is there meaningful upside left?
Most Popular Narrative: 13% Undervalued
Ecolab last closed at $281.69 while the most followed narrative points to a fair value of $324.95. The current price sits below that modeled estimate and keeps the spotlight firmly on whether its growth engines can do the heavy lifting implied by that gap.
The main factor that has to go right is that Ecolab sustains high growth and strong margins in Global High-Tech, Life Sciences, Digital and Pest while executing high capital expenditure and integrating CoolIT, so that these engines lift group operating margins toward at least 20% and support ongoing organic ROIC expansion.
See why 50 investors see Ecolab as 13% undervalued.
Result: Fair Value of $324.95 (UNDERVALUED)
Still, the Ecolab story comes with pressure points, from softer heavy industrial demand to higher tariffs and input costs that could strain the value-based pricing playbook.
Find out about the key risks to this Ecolab narrative.
Another View: What Ecolab’s P/E Is Telling You
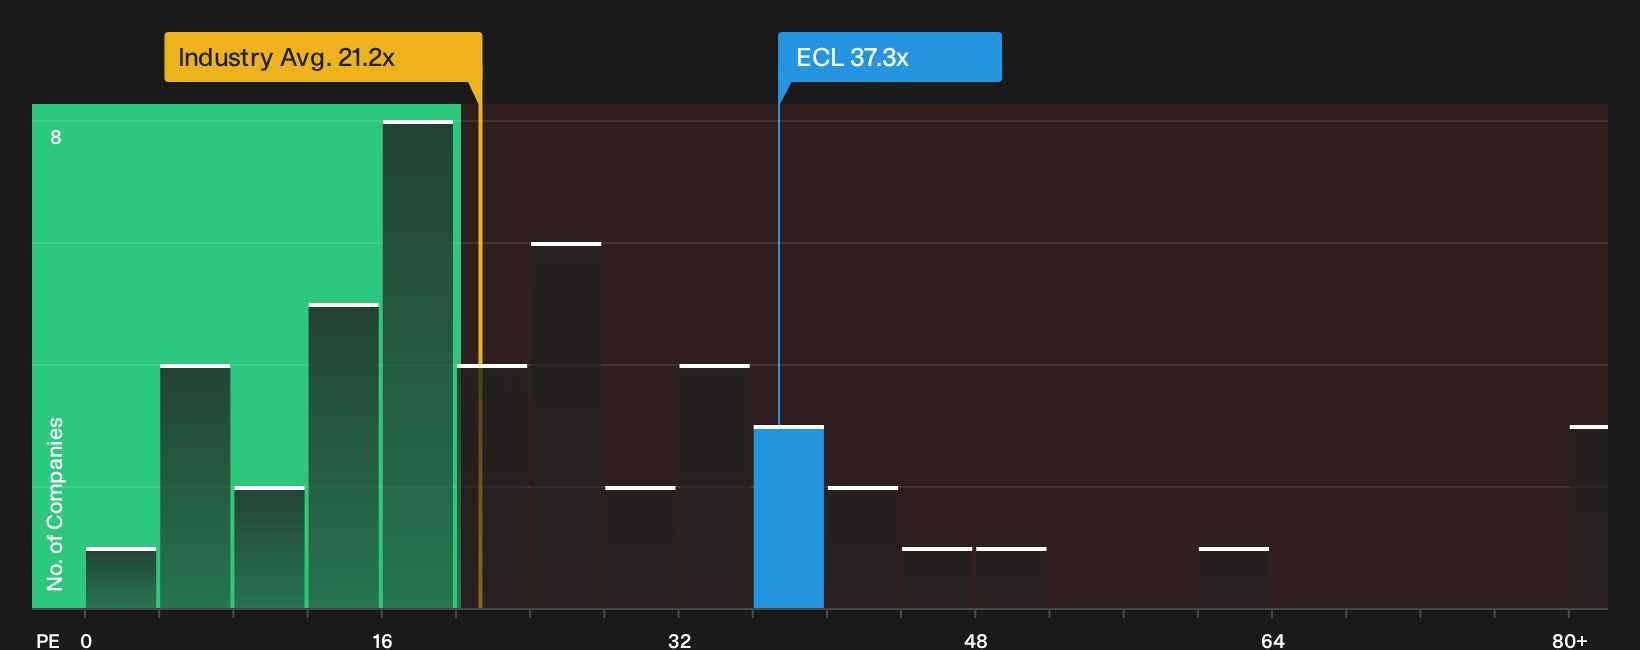
There is a very different message when you look at Ecolab through its P/E. The stock trades on 37.3x earnings versus 18.9x for peers and a fair ratio of 23.7x, which points to a rich tag and raises the question of how much execution risk you are really willing to carry.
To see how that premium lines up with the underlying numbers, take a look at the detailed valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
For a visual sense of how far Ecolab’s current earnings multiple stretches beyond the sector and that fair ratio, review the comparison chart in
Next Steps
If the mixed signals around Ecolab leave you on the fence, move quickly from headline impressions to hard data and stress test the thesis yourself with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Ecolab?
If Ecolab sharpened your focus on quality and valuation, you may want to broaden your watchlist with a few targeted stock pools that match different investing angles and risk appetites.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) for companies built to handle tougher conditions.
- Look for potential mispricing by reviewing the 27 high quality undervalued stocks that combine stronger financial quality with more modest expectations.
- Prioritise income and staying power by checking out the 8 dividend fortresses that focus on higher yields backed by more durable profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com