
- VEON announced a 10 year agreement with Amdocs to modernize its core technology operations and support digital services across Eurasian markets.
- The deal formalizes long term access to Amdocs’ AI driven aOS platform, tying VEON’s digital revenue ambitions directly to outsourced technology execution.
- The focus now is on how VEON's investment narrative could shift as long term digital execution increasingly depends on the Amdocs partnership.
VEON Investment Narrative Recap
To own VEON, you need to believe its shift from classic telecom to digital services and fintech in markets like Pakistan and Bangladesh can offset thinner margins and heavy investment needs. In the near term, the key factor is execution in core geographies while managing currency swings and debt, rather than relying on any single contract or partnership.
The Bangladesh digital bank license and the Amdocs deal both reflect the same thesis: that VEON can use connectivity as a springboard into higher value digital ecosystems. The main operational risk remains unchanged. Profitability is thin, interest costs are sensitive, and asset sales have already reduced the revenue base.
The digital bank approval in Bangladesh is the clearest operational link to VEON’s current news flow. It extends the existing Mukto Pay PSP setup toward full service banking, adds another element to the fintech story alongside products such as JazzCash, and deepens integration with Banglalink’s mobile users as VEON focuses more on fee based services.
As a potential catalyst, this banking license provides a concrete test case for VEON’s broader digital strategy. It combines foreign direct investment commitments, a local partnership with Square Group and mobile distribution into a single project. Execution quality in this initiative, including credit risk controls and customer adoption, will influence how investors assess similar fintech and super app efforts across the group.
What The Analyst Case Implies For VEON
VEON's analyst narrative points to US$6.2b in revenue and US$730.9m in earnings by 2029. That profile lines up with an assumed 9.2% yearly revenue growth rate and an earnings rise of about 12x from US$59.0m today to the 2029 consensus figure.
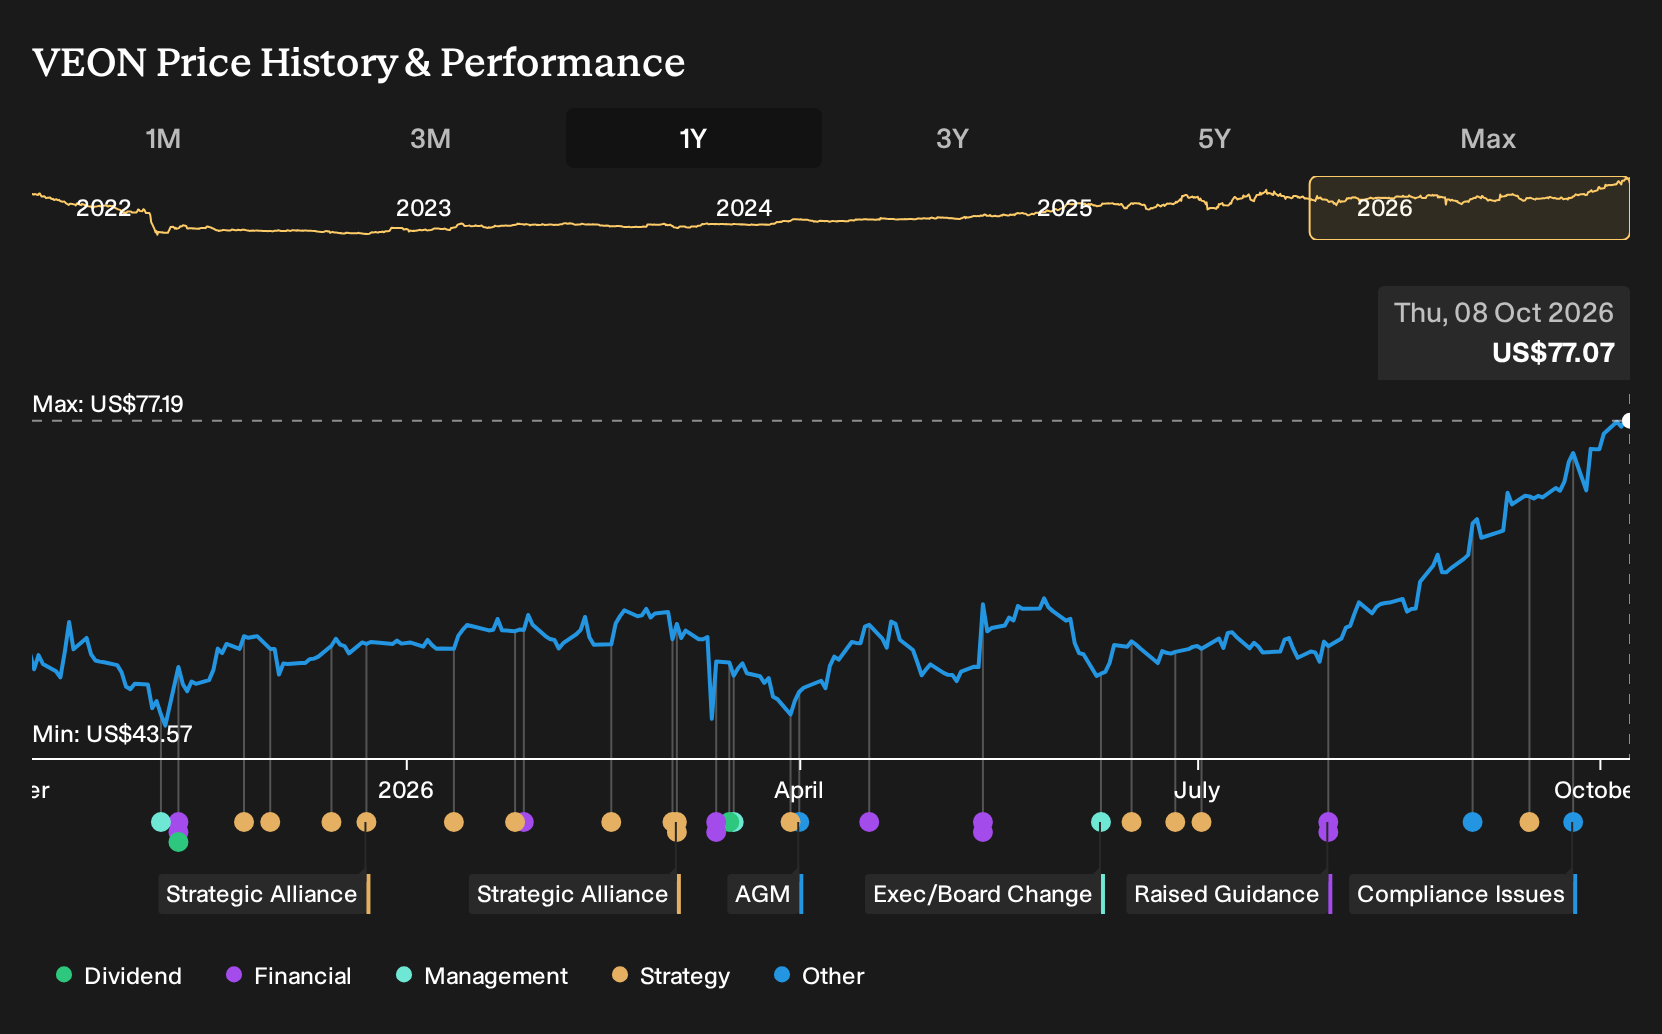
Uncover why VEON's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The lowest VEON forecasts lean heavily on execution risk. Those bearish analysts saw revenue nearer US$5.8b by 2029 and earnings around US$657.0m, which is well below the consensus path. You can read that as a warning that digital banking and the Amdocs AI push might still reshape those expectations, in either direction.
Explore 4 other VEON fair value estimates, including one that suggests as much as 34% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your VEON research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for VEON. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate VEON's overall financial health at a glance.
Looking For More Ideas Beyond VEON?
If VEON has sharpened your interest in digital platforms, it can help to compare it with other businesses that match the kind of balance sheet strength, value profile, or income focus you want in your portfolio. The Simply Wall St Screener makes it easier to filter for those traits instead of relying on headlines or single stories.
- If capital preservation sits high on your list, scan a curated set of resilient companies through the 31 resilient stocks with low risk scores that aim to pair stability with measured growth potential.
- If value and fundamentals matter most to you, sift for mispriced businesses with strong cash flows using the 20 high quality undiscovered gems that highlights quality operators flying under most investors' radars.
- If you want income to play a bigger role in your returns, go to the 8 dividend fortresses that focuses on higher yielding payers with an eye on durability as well as headline yield.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com