
Bond specialists now see the 10 year US Treasury yield as capable of hitting 6%, which keeps pressure on borrowing costs and makes dependable income harder to find. That backdrop puts a spotlight on companies that already pay solid, regular cash out to shareholders. In this article, you will see three high yielding dividend payers from our income screen that prioritises coverage, consistency and steady growth.
The three stocks that follow are just a small sample, as the full Dividend Powerhouses screen surfaced 168 more income ideas with solid yields and compelling stories that are not covered here.
If you want to identify, analyze, and refine your own list of high conviction dividend plays, head straight to the Dividend Powerhouses (3%+ Yield) screener.
DRDGOLD (DRD)
DRDGOLD is a South African gold producer that extracts gold from surface mine tailings, a cash generative retreatment activity that underpins its dividend profile. Most revenue comes from the Ergo operation at ZAR 8.1b, with FWGR adding ZAR 3.1b, and the business carries a market value of about US$2.1b.
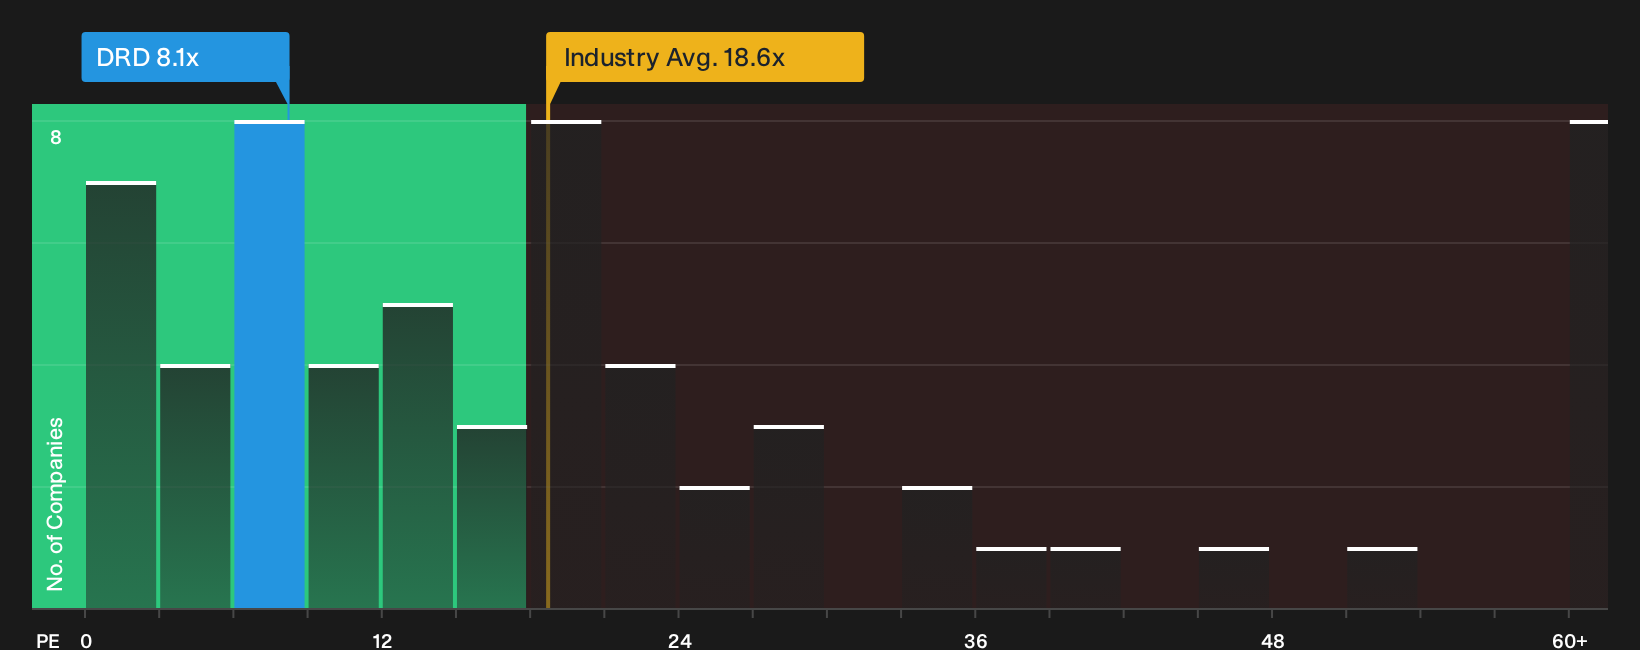
For dividend hunters, DRDGOLD presents an income story built on tailings retreatment that feeds directly into cash distributions, supported by a P/E of 8.1x and a net profit margin of 38.1%. The appeal of that yield depends on how one less visible pressure shapes the actual cash flowing through to those payouts.
Those cash flows are only half the story, so take a look at the 2 key rewards and 2 important warning signs (1 is major!) to see what might accelerate or choke that payout stream.
Brown-Forman (BF.B)
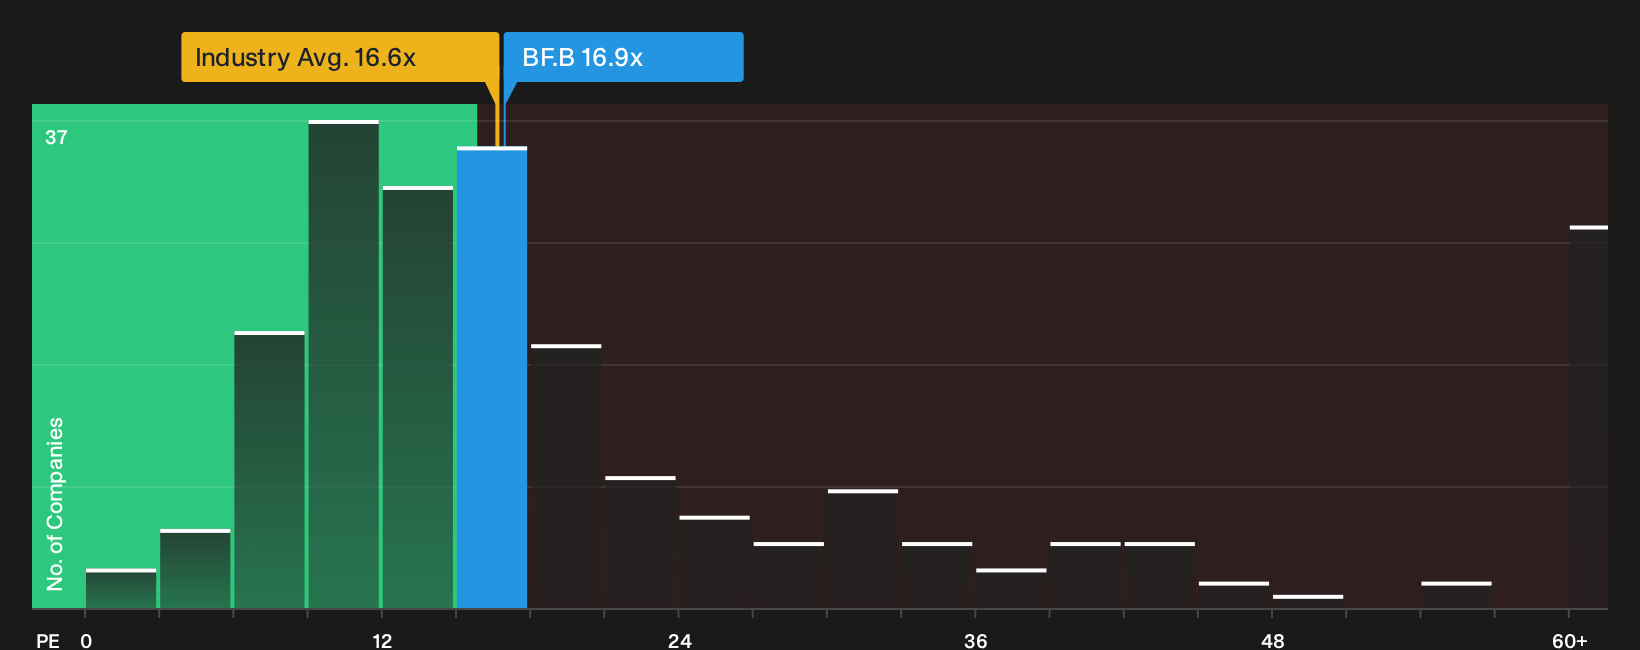
Brown-Forman leans on its long-established Jack Daniel’s led spirits portfolio to produce dependable cash flow, which in turn supports a 3%+ dividend profile. This is built on a single beverage alcohol segment generating about US$3.9b in sales and backed by a market value near US$12b.
Brown-Forman illustrates how a mature drinks group can still grow its dividend story by focusing on brand loyalty and new formats rather than relying solely on volume growth.
"Growth in ready to drink products like New Mix, el Jimador Spritz and Jack Daniel’s Tennessee Blackberry, which together are adding multi point value growth contributions in key markets, is creating a higher volume platform that can add to revenue while partially offsetting the impact of softer full strength spirits demand on operating income."
What that means for Brown-Forman’s dividend power ultimately hinges on how one quiet cost pressure develops over the next few years.
That quiet cost pressure is only part of the story, and the full narrative for Brown-Forman explains how it interacts with pricing power, premiumisation, and potential capital returns.
Accenture (ACN)
Accenture focuses on long-term cloud, data and AI, and managed services work that brings in steady, high-margin fees. This supports its place in a dividend screen focused on well-covered, consistent payouts rather than one-off project wins.
Accenture runs a global consulting and outsourcing platform across products (about US$22.5b), financial services (about US$14.0b), health and public service (about US$15.2b), resources (about US$9.9b), and communications, media and technology (about US$12.7b), with the whole group valued around US$117.2b.
"The market is asking whether Accenture can convert AI from a threat into a growth engine."
How that tension affects its largest AI-heavy contracts could influence everything from day rate leverage to long-run dividend headroom.
That dividend headroom question is where it gets interesting, and the full narrative for Accenture maps how Accenture could turn rising AI demand into accelerating fee power and steadier cash returns.

Seeking Fresh Alternatives For Your Income?
Fresh dividend and quality ideas can move from quiet to crowded fast. Spot potential breakouts and steady compounders while they are still under the radar for now, and consider getting in at an early stage.
- Focus on durable balance sheets and disciplined cash generators using the curated list of solid balance sheet and fundamentals (25 results) before the crowd starts chasing the next wave of momentum.
- Explore potential future infrastructure candidates as demand builds around electrification by reviewing a focused set of 43 power grid technology and infrastructure stocks while prices still reflect early interest.
- Monitor the shift toward reliable income streams and structural scarcity by scanning carefully selected 33 best rare earth metal stocks before valuations are heavily influenced by sentiment.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com