
Axcelis Technologies has been on a strong multi year share price run, and that raises a straightforward question for you as an investor: Is the current valuation supported by what the business is actually earning today?
- Over the past 5 years the stock has returned 196.2%, which puts a lot of weight on whether its earnings profile can support that kind of re-rating.
- The planned US$35m ion implantation factory in Korea and the pending Veeco merger can reshape Axcelis Technologies' future earnings mix, timing and capital requirements, which all matter when you compare its P/E to the Fair Ratio benchmark.
- The analysts covering Axcelis Technologies have run their own numbers. See what analysts think Axcelis Technologies's shares could be worth.
The issue now is whether Axcelis Technologies' recent share price level is justified by the earnings power investors are paying for today.
If you are weighing Axcelis Technologies against other potential ideas built around solid earnings support, it can help to compare it with companies in the 27 high quality undervalued stocks
Does Axcelis Technologies Look Pricey on Earnings?
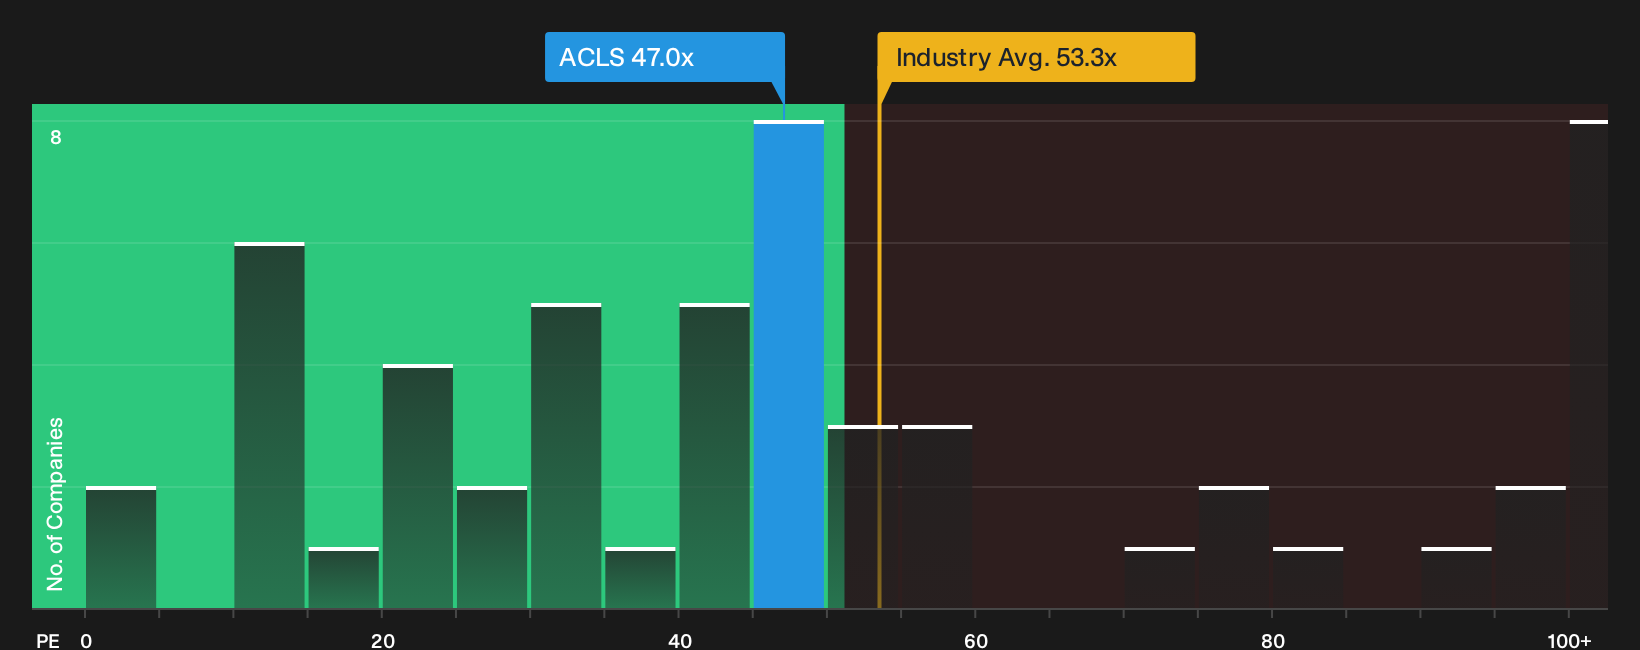
The P/E lens fits Axcelis Technologies because earnings remain the main anchor investors are using to judge the stock. The current P/E of 47.0x sits below the Semiconductor industry average of 53.3x and well under the peer group on about 64.8x, so the share price is not at the top of the sector range even after its strong run.
The Fair Ratio, which is the multiple you might expect once Axcelis Technologies' growth profile, margins, size and risk are all baked in, screens lower than the live P/E, so on this framework the stock looks overvalued. Because the US$35m Korea plant and the pending Veeco deal both pull forward spending before the earnings benefits fully show up, the current P/E asks you to pay a premium versus that tailored benchmark for those future payoffs. Despite that expansion narrative, the ratio still implies investors are accepting a richer price on earnings than the Fair Ratio model supports. Explore the numbers behind Axcelis Technologies's P/E valuation.
The Axcelis Technologies Narrative: What Would Justify Today's Price?
Narratives for Axcelis Technologies on Simply Wall St's Community page pick up where the P/E puzzle leaves off by spelling out which earnings, margin and growth paths would need to play out for the stock to look meaningfully cheaper or more expensive than it does today. Each one links its implied value to a specific view on how Axcelis Technologies' growth, profitability and risk profile evolve, which you can test again as fresh information comes through.
Community views on Axcelis Technologies are split between those who see more upside in the current setup and those who think expectations already run high.
Bull case: 12% undervalued
"As the installed base of Axcelis Technologies tools grows, recurring revenue from higher margin services, parts and upgrades through CS&I continues to increase…"
Discover why this Narrative puts Axcelis Technologies at 12% undervalued.
Bear case: roughly fairly valued
"The company anticipates lower non GAAP gross margins in 2026 in the low to mid 40% range due to a heavier mix of memory systems and incremental tariff costs…"
Explore why this Narrative puts Axcelis Technologies at roughly fairly valued.
One more Axcelis Technologies angle that could change how you see the stock
Everything so far has focused on what Axcelis Technologies earns today. However, professional estimates for where the business might be a few years out give you a separate yardstick to measure against the current share price. Explore where analysts expect Axcelis Technologies to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com